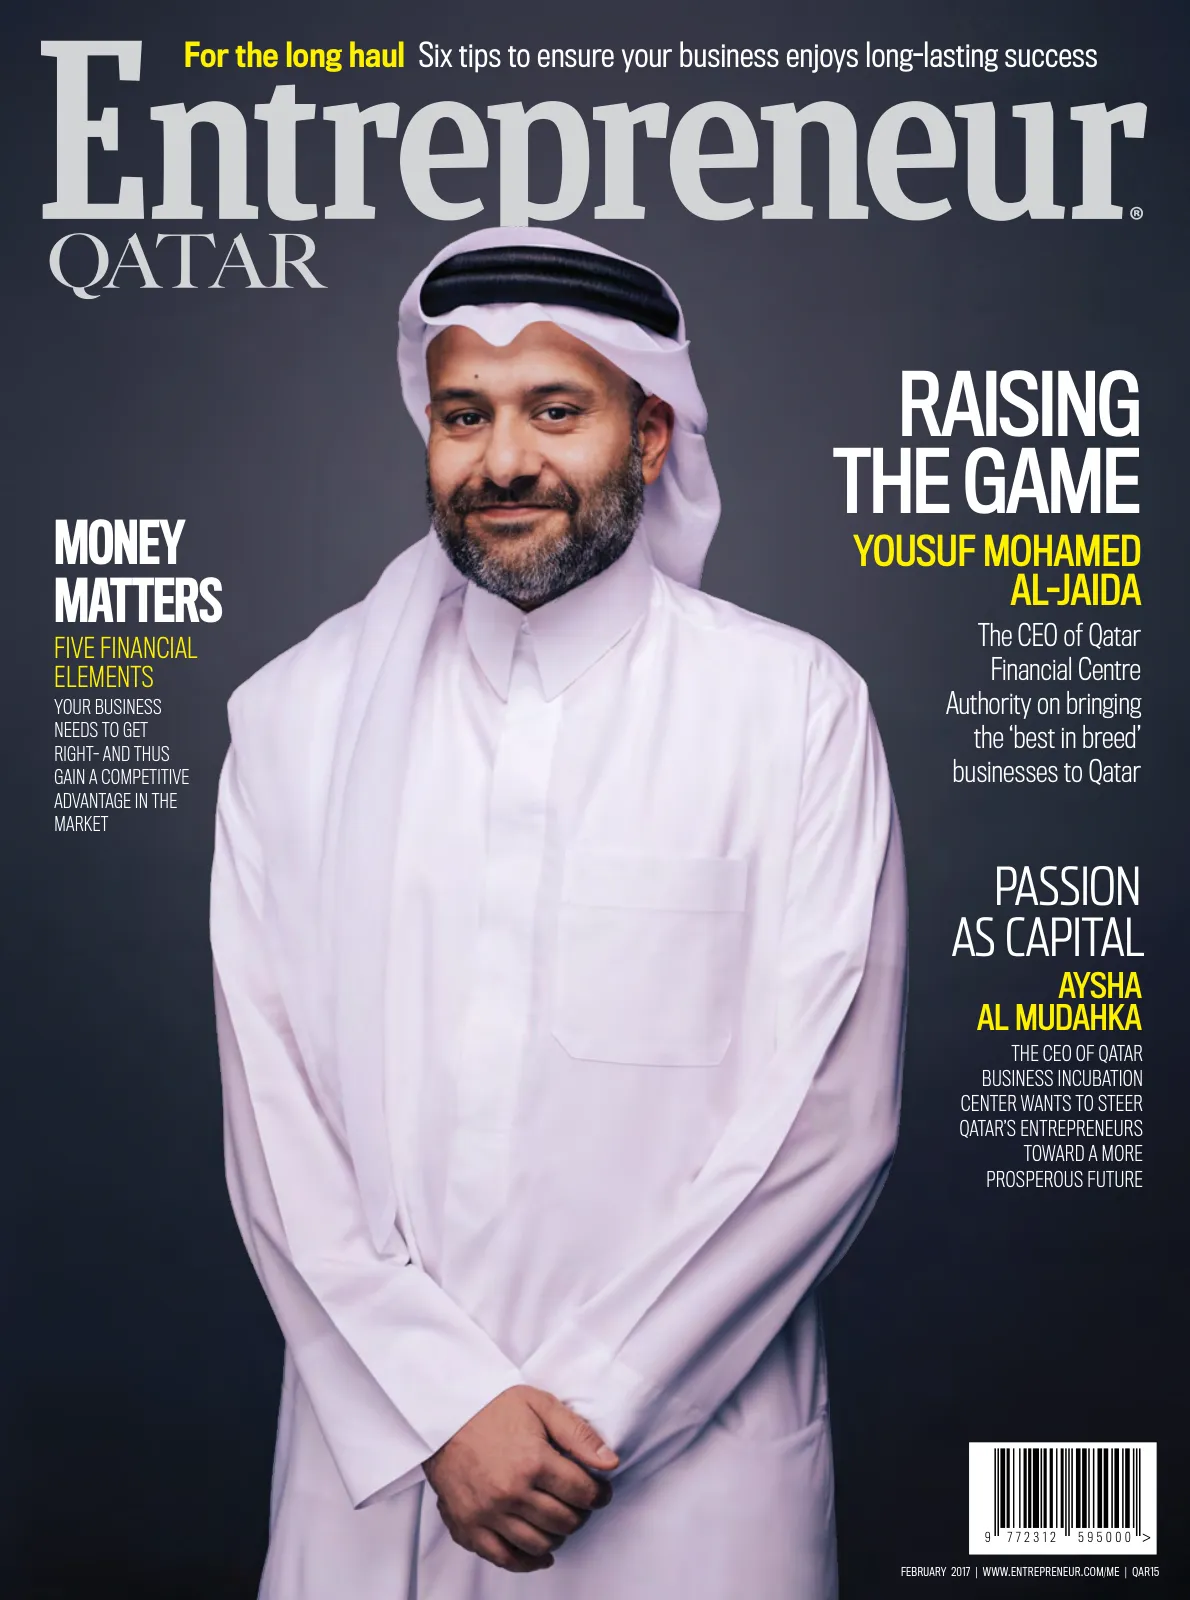
Entrepreneur Qatar, February 2017
Page 1
For the long haul Six tips to ensure your business enjoys long-lasting success
raising
the game
The CEO of Qatar
Financial Centre
Authority on bringing
the ‘best in breed’
businesses to Qatar
Aysha
Al Mudahka
Passion
as capital
The CEO of Qatar
Business Incubation
Center wants to steer
Qatar’s entrepreneurs
toward a more
prosperous future
Money
matters
your business
needs to get
right- and thus
gain a competitive
advantage in the
market
Five financial
elements
Yousuf Mohamed
Al-Jaida
9
7 7 2 3 1 2
5 9 5 0 0 0 >
FEBRUARY 2017 | www.entrepreneur.com/me | QAR15
Page 2
Page 3
february 2017 Entrepreneur
3
24
Aysha Al Mudahka, CEO, QBIC
CONTENTS
february 2017
18
18
INNOVATOR:
Raising the game
Qatar Financial Centre
Authority CEO Yousuf
Mohamed Al-Jaida on
bringing the ‘best in breed’
businesses to Qatar.
24
INNOVATOR:
Passion as capital
Qatar Business Incubation
Center CEO Aysha Al
Mudahka wants to steer
Qatar’s entrepreneurs toward
a more prosperous future.
28
‘TREPONOMICS:
PRO
The entrepreneur’s HR
playbook
A three-part guide to best
practices in HR for all stages
of your business.
68
START IT UP:
ECOSYSTEM
Ramesh Jagannathan,
Managing Director of
startAD, the innovation and
entrepreneurship platform
at NYU Abu Dhabi, lists
three steps to building a
sustainable entrepreneurial
economy in the UAE.
74
START IT UP:
Q&A
Keeping things local
Jordan-based CashBasha
enables MENA shoppers
to shop on international
e-commerce portals like
Amazon- with cash.
44
TECH:
SHINY
#TamTalksTech
Gadgets and doodads
that you might’ve missed
out on, sourced by a tech
aficionado. Yes, it’s okay to
want them all… and no, it’s
not our fault.
Yousuf Mohamed
Al-Jaida, CEO,
Qatar Financial
Centre Authority
Page 4
Page 5
Page 6
Entrepreneur february 2017
6
CONTENTS
80 Lilian Barbosa, Haya Al Ghanim and Amina Ahmadi,
co-founders, Oola Sports
february 2017
60
MONEY:
ASK THE MONEY GUY
Maximizing value
Investor, advisor, and
entrepreneur Ara Sahakian
explains four strategies
you can use to better your
business’s chance of a
successful exit.
66
START IT UP:
ECOSYSTEM
The generation gap
Entrepreneurs Paul Kenny
and Rajesh Sajnani compare
and contrast old school
practices with millennial
outlooks on starting your
own business.
82
‘TREPONOMICS:
SKILLSET
For the long haul
Appetite Group co-founders
Suzi Croft and Manar Al
Jayouchi list six ways to
ensure long-lasting success
for your business.
14
EDITOR’S NOTE
By Aby Sam Thomas
62
MONEY:
VC VIEWPOINT
Moving ahead
Jon Richards, co-founder
and CEO of compareit4me.
com, on why the UAE’s new
venture capital regulations
will help the ecosystem.
48
‘treponomics:
ESQUIRE GUY
Are you avoiding the
telephone?
The Esquire Guy wants you to
stop texting and emailing- and
start calling instead.
36
The Ford booth at
the CES show in Las
Vegas, January 2017
ford ces image © kooby dagan / shutterstock
44 Sony Portable
Ultra Short Throw
Projector
Page 7
Page 8
Entrepreneur february 2017
8
CONTENTS
february 2017
78
David Llorente,
CEO, Narrativa at
48 Forward
74 CashBasha team wins at Startup Istanbul 2016
52
CULTURE:
LIFE
Lost in translation
Unisono’s Founding
Partner Liam Farrell
offers a checklist that
can help you better your
communication in the
multicultural Middle East.
72
START IT UP:
ECOSYSTEM
Calling fintech
entrepreneurs
Global consulting firm
Accenture has joined hands
with Dubai International
Financial Centre (DIFC) to
launch FinTech Hive.
78
START IT UP:
Q&A
Weaving stories from data
UAE-based natural
language generation startup
Narrativa uses AI to
generate content at scale.
50
CULTURE:
LIFE
Making good habits stick
James Clear explains how
the “Paper Clip Strategy”
can help you to stop
procrastinating on your
goals.
46
CULTURE:
TRAPPINGS
‘Trep gear
The executive selection for
the entrepreneur on your
list. Okay, maybe for a little
self-reward as well.
56
MONEY:
YOUR MONEY
Money matters
Athena CFO co-founders Dr.
Christiane Schloderer and
Heather Henyon explain the
five key financial elements
that can endanger your
venture if not managed
properly.
46 TAG Heuer
Carrera Caliber
16 Day-Date
Chronograph
Black Titanium
Page 9
Page 10
Entrepreneur february 2017
10
SUBSCRIBE
Contact subscriptions@bncpublishing.net to receive
Entrepreneur Middle East every issue
EDITOR IN CHIEF Aby Sam Thomas editor@bncpublishing.net
CEO Wissam Younane wissam@bncpublishing.net
MANAGING DIRECTOR Walid Zok walid@bncpublishing.net
DIRECTOR Rabih Najm rabih@bncpublishing.net
CREATIVE LEAD Odette Kahwagi
STARTUPS SECTION EDITOR Pamella de Leon
COLUMNIST Sindhu Hariharan
COLUMNIST Tamara Clarke
COLUMNIST Shoug Al Nafisi
SENIOR JOURNALIST Aparajita Mukherjee
EVENTS LIAISON Mark Anthony Monzon
PO Box 502511 Dubai, United Arab Emirates
P +971 4 4200 506 | F +971 4 4200 196
For all commercial enquiries related to
Entrepreneur Middle East contact
sales@bncpublishing.net
All rights reserved © 2016.
Opinions expressed are solely those of the contributors.
Entrepreneur Middle East and all subsidiary
publications in the MENA region are officially licensed
exclusively to BNC Publishing in the MENA region by
Entrepreneur Media Inc.
No part of this magazine may be reproduced or
transmitted in any form or by any means without written
permission of the publisher.
Printed by Raidy Emirates Printing Group LLC
www.raidy.com
Images used in Entrepreneur Middle East are credited when necessary. Attributed use of
copyrighted images with permission. All images not credited otherwise Shutterstock.
Manar Al-Jayouchi
Suhail Al Masri
Fida Chaaban
James Clear
Suzi Croft
Liam Farrell
Heather Henyon
Ramesh Jagganathan
Paul Kenny
Kristofer Kumfert
Ross McCammon
Neil Petch
James Randall
Jon Richards
Ara Sahakian
Rajesh Sajnani
Dr. Christiane Scholderer
Anton Van Der Walt
CONTRIBUTING WRITERS
www.entrepreneur.com/me
Access fresh content daily on our website!
MIDDLE EAST
EntMagazineME
@EntMagazineME
Entrepreneur-me
EntrepreneurMiddleEast
EntMagazineME
EntMagazineME
EntMagazineME
In addition to our print edition, we’re bringing
you all sorts of industry news on our web
mediums. Joining us online means getting
relevant business and startup content in
real-time, so you’re hearing about the latest
developments as soon as we do. We’re looking
forward to interacting with our readers on all of
our social media and web platforms- like any
thriving business, we’re looking to give and take.
#TrepTalkME is already happening on all of our
digi platforms, and all good conversations go
both ways. See you on the web!
Page 11
IN 1934, BRITANNIA DIDN’T JUST RULE THE WAVES
On October 22nd 1934, two exhausted airmen landed on a racecourse in Melbourne, surrounded by
cheering crowds. Flying a specially-built De Havilland Comet DH-88, Charles Scott and Tom Campbell
Black set a new record, flying the 11,000 miles from England in just 71 hours. The Bremont DH-88
commemorates their aircraft and their achievement. Containing actual material from the record-breaking
plane, the Bremont DH-88 is available now in a strictly limited edition. But it won’t be available for long.
Fifty One East · Doha, Qatar · T: +974 4436 1111
Page 12
Entrepreneur february 2017
12
EDITOR’S NOTE
Aby Sam Thomas
Editor in Chief
@thisisaby
aby@bncpublishing.net
Ambition overdrive
Your ideas are great- but do you also know how
to get them implemented?
I
love people who come to me
with ideas.
But I hate people who come to
me with only ideas.
Does that make any sense? I feel
like the above sentiment will strike
a chord with those of you who work
with those amazingly imaginative
folk who are seemingly always
abounding with ideas on how the
business can do better for itself. I’ve
found that these apparently enter-
prising thinkers are often the bosses
or entrepreneurs running the show,
and as a result, one feels almost
obliged to take their thoughts
seriously, given that it was their
ideas that got the whole enterprise
started in the first place.
However, as the oft-repeated
aphorism goes, ideas are worth
nothing if not executed properly,
and a complaint that I often hear
from people who work at startups
and corporates alike is how their
employers come up with fantastic
new schemes to build up their
companies, but then fail to offer
any sort of roadmap or plan for the
same. After all, such ideas require
time, resources, and yes, a lot of
work to be properly implemented-
but more often than not, such
considerations are sadly overlooked
or ignored. And when this happens,
the workforce -especially those at a
startup- find themselves grappling
with the extra workload, which then
soon leads to things falling through
the cracks, and a pervading sense of
frustration in the team at large.
So how do you avoid this from
happening in your enterprise?
Well, I’m no management expert,
but the answer, I think, lies in first
respecting the people you have on
board, and the work that they do for
you. Sure, it’s important that you,
as the leader, keep spurring your
employees to go above and beyond
what they might think themselves
capable of doing, but do understand
that there are limits to how much
you can do this as well. Take time
to understand your personnel’s
day-to-day workloads, and know
that for every new task you throw
on their heads, they have to reas-
sign time and resources from their
existing ones. Being appreciative
of this will allow you to add a dose
of reality to the ideas you come up
with for building up your company-
this way, you won’t affect business
as usual, and your team morale will
stay positive as well.
By the way, all of this is not to say
that you should put a stop to the
stream of ideas that flow out of
you- my only suggestion is that you
devise plans for their execution as
well. Doing that will see you better
equipped to realize those ambitions
of yours- and that’s always a good
thing.
Page 13
Page 14
Entrepreneur february 2017
14
Q
atar Chamber of Com-
merce and Industry
(QCCI) organized the
2nd SMEs Conference
at The Ritz Carlton
Doha in January, which was
held under the patronage of
Prime Minister and Interior
Minister, H.E. Sheikh Abdul-
lah bin Nasser bin Khalifa
Al-Thani, and inaugurated
by Deputy Prime Minister
and Minister of State for
Cabinet Affairs, H.E. Ahmed
bin Abdullah bin Zaid Al
Mahmoud.
This year’s edition of the
conference was held under
the framework of economic
partnership between Qatar
and Turkey, represented
by the Union Chambers
and Commodity Exchanges
of Turkey (TOBB). The
event saw QCCI and TOBB
make a cooperation agree-
ment, signed by the QCCI
Chairman Sheikh Khalifa
bin Jassim Al-Thani and
TOBB president M. Rifat
Hisarcıklıoglu, with the aim
of strengthening cooperation
between the two agencies,
develop its small and me-
dium sized enterprise sector,
and facilitate exchange of
best practices in the SME
industry.
In his address to the
audience, Qatar Chamber
Chairman Sheikh Khalifa bin
Jassim bin Mohammed Al-
Thani, who is also Chairman
of the Board of Directors of
the International Chamber
of Commerce in Qatar, said
that the country had realized
the importance of the role
played by the SME sector,
and hence has modernized
legislations and promoted
initiatives to enable these
businesses to increase their
contribution to the gross
domestic product.
With respect to the subject
of funding for SMEs, Khalid
Al Mana, Executive Direc-
tor of Business Finance of
Qatar Development Bank
(QDB), noted, “It all boils
down to risk, and QDB works
with local banks to provide
guarantees, though we do
not work on a day-to-day
basis on funding SMEs. Our
guarantees serve the twin
purpose of SME develop-
ment, and promoting lending
to the sector.” At the same
time, Salvino Salvaggio,
Research Director – ICT, at
Qatar Science & Technology
Park (QSTP), noted how his
organization was helping
change the landscape for
SMEs in the country. “95-
97% of the private sector
in countries such as Qatar
are SMEs, in recognition
of which we, at QSTP, have
established a product devel-
opment fund to help fund
SMEs.”
The recap: Qatar Chamber’s 2nd SMEs Conference
Impacting the economy
in pictures
images courtesy qatar Chamber of Commerce and Industry
By Aparajita Mukherjee
Page 15
Porto Arabia Towers
Doha, Qatar
������������������������������
Hill International
The Global Leader in Managing Construction Risk
www.hillintl.com
�����������������������������������������������������������������������
���������������������������������������������������������������������
��������������������������������������������������������������������������
������������������������������������������������������������������������
�������������������������������������������������������������������������
���������������������������������������������������������������������
��������������������
����������������������������������������������������������������������������
���������������������������������������������������������������������
�������������������������������������������������������������������������
�����������������������������������������������
��������������������������
�������������������������
��������������������������
If you can imagine it, we can manage it.
��������������������
Doha, Qatar
��������������
Doha, Qatar
Viva Bahriya Towers
Doha, Qatar
Page 16
Entrepreneur february 2017
16
IN THE LOOP
Stepping up
STEP Group raises US$2 million in funding from
regional and global investors
We have a winner!
NOW Money will represent the GCC
at The Venture 2017
Ray Dargham, co-founder
and CEO, STEP Group
A team at the Enterprise
Challenge Qatar
image source: step group | chivas the venture
NOW Money’s Katharine Budd and Ian Dillon, winners of
Chivas The Venture Gulf Regional Final
A
fter months of search, pitches and selections,
the hunt is over- NOW Money was selected as
the winner of the GCC edition of The Venture
2017, a global social entrepreneurship competition
seeking innovative startups with social impact and
viable business model, at a ceremony conducted
on January 18, 2017 at the Intercontinental Dubai
Marina Hotel. Founded by duo Katharine Budd and
Ian Dillon, the fintech app offering an alternative to
banks and remittance fees for low-income employees
competed against three other finalists: Health Gate,
a developer for non-toxic and chemical-free sanitary
products for women and children; ilovemypocket, a
lifestyle brand enabling its consumers to donate to
education-centered NGOs; and Chari Cycles, a brand
upcycling vintage and used bicycle frames, while
funding bicycles for children in Middle East refugee
camps.
Organized by Chivas, the finals of The Venture
GCC 2017 consisted of a pitching round and a
Q&A portion with the competition’s judges, which
consisted of Yogesh Mehta, Managing Director of
Petrochem Middle East; Soushiant Zanganehpour,
founder of Tribeca Impact Partners; Charles Blaschke,
co-founder of Taka Solutions and winner of The
Venture 2016 GCC; Jeremy Lawrence, Editor in
Chief of Esquire Middle East, and Gaurav Sabharwal,
Managing Director of Pernod Ricard Gulf, who
commented on NOW Money’s scalability and social
impact potential as essential factors to their win.
For the GCC 2017 winner, the journey is just
beginning- NOW Money is one of 30 startups
competing in the global finals of The Venture.
Next up, besides mentorship opportunities, NOW
Money will be heading for a training camp at the
University of Oxford by the Skoll Centre for Social
Entrepreneurship in the UK in March, and finally,
they would be heading for the finals in Los Angeles,
US in July to pitch for a chance for a share of the
US$1 million funding prize. Given that they represent
the GCC, here’s to the region rooting for NOW
Money- all the best!
S
TEP Group, the organizer of
STEP Conference, one of the
largest technology events in
the Middle East, has closed
a Series A funding round of
US$2 million from investors includ-
ing Wamda Capital, Equitrust, Dubai
Silicon Oasis Authority, and global
VC firm North Base Media. The
startup, which also owns news and
entertainment platforms stepfeed.
com, yallafeed.com, and the recently
acquired video platform Arab Vines,
believes that the deal is a shot in the
arm both for the group’s ambitions
to “build the #1 modern and tech
powered new media company in
MENA,” and the region’s larger new
media space.
In a state-
ment on the
fundraise,
STEP Group
co-founder &
CEO Ray Dar-
gham said that
the financial
support will be
used to bridge
“a growing gap
between Arab
millennials and
the mainstream media” with a “dy-
namic” media platform. “We aim to
more than quadruple the user base
across our platforms within the next
twelve months to reach more than
10 million users and 30+ million
monthly views, and further develop
our recently launched STEP Video
capability,” said Dargham. Speaking
to Wamda, he added that he “was
inspired by global models, looking to
replicate the Vox model of a platform
that uses multiple industry verticals,
and the Buzzfeed creativity when
producing content.”
Industry reports suggest that while
the appetite for digital Arabic con-
tent in modern formats is increas-
ing among millennials, there is a
large market gap when it comes to
platforms supplying them. Khaled
Talhouni, Managing Partner, Wamda
Capital, believes that STEP Group
has “recognized and taken owner-
ship” of this growing need. “This
investment comes as part of Wamda
Capital’s thesis of investing in
unique and emerging regional digital
assets that are founded and managed
by extraordinary entrepreneurs,” he
said in a statement.
Interestingly, STEP Group rep-
resents the first investment in the
Middle East for North Base Media,
a media industry-focused VC firm.
Besides STEP’s recent inroads into
video content through Arab Vines,
this year’s STEP Conference (an
event which is said to have tripled
in size since it began in 2012) will
include the launch of STEP Music- a
concept created in partnership with
Middle East music streaming service
Anghami to bring together record
labels, producers and artists to
explore trends and challenges facing
the industry.
www.stepconference.com
Page 17
Page 18
Entrepreneur february 2017
18
T
he Qatar Financial
Centre (QFC) has
come a long way
since its incep-
tion in 2005, be
it with the continuous
development of its corporate
strategy, the widening of its
platform, or the permitted
activities and regulations.
In explaining the basic
function of the QFC, Yousuf
Mohamed Al-Jaida, CEO
of Qatar Financial Centre
Authority, says that QFC is
“neither an offshore centre,
nor a free trade zone, but an
onshore platform,” noting
how it enables international
firms to operate in Qatar
without restrictions on cur-
rency or trade, and under
one of the most favorable tax
environments in the world.
But Al-Jaida is quick to
clarify that QFC is not just a
platform for enterprises out-
side of Qatar. “A financial
and business centre can’t
just be created by attract-
ing foreign companies. To
be a true business centre,
Qatar needs to nurture and
support the growth of local
companies as well. The QFC
plays an important role in
supporting this aspect of
Qatar’s growth- more than
30% of our licensed com-
panies are local; in our con-
versations with them, these
local firms acknowledge the
QFC’s robust legislation as
an important facilitator in
their success as they expand
in Qatar and beyond.” >>>
INNOVATOR
Ahmad
Hanandeh,
CEO, Zain
Jordan
Raising
the game
Yousuf Mohamed Al-Jaida
The CEO of Qatar Financial Centre Authority
on bringing the ‘best in breed’ businesses to Qatar
By Aparajita Mukherjee
Page 19
february 2017 Entrepreneur
19
Qatar Financial
Centre Authority
CEO Yousuf
Mohamed Al-Jaida
Page 20
Entrepreneur february 2017
20
Since 2005, the QFC has li-
censed over 300 firms, with
approximately QAR75 billion
in assets, with those firms
distributing over QAR1.5
billion in salaries per year.
“Several of these institutions
began by providing services
in Qatar without immedi-
ately having a formal pres-
ence here. So an important
benefit to the local economy
is that QFC is a catalyst to
on-shoring businesses,”
explains Al-Jaida. “Recently,
Qatar First Bank became the
first Qatari QFC-licensed
firm to be listed on the Qatar
Exchange. This and several
other local success stories
add to the real impact that
the QFC has on Qatar’s econ-
omy.” The QFC Law provides
for a broad range of activities
to be conducted in or from
the QFC- these include non-
regulated activities (that do
not require extensive super-
vision), whereas regulated
activities (those conducted
by financial service firms,
such as banking, insurance
or securities businesses)
require close and continuing
scrutiny to ensure prudential
soundness and the proper
conduct of those businesses.
Classifying the several
kinds of companies within
QFC, Al-Jaida mentions that
several of these companies
are specialist companies op-
erating in knowledge-based
industries, for example
research services (Bloomberg
& Thomson Reuters), valu-
ation services (ValuStrat)
and Management consulting
(PWC, McKinsey). “Their
presence in Qatar facilitates
information sharing and
capacity transfer to the
local economy,” says Al-
Jaida. While the size of a
company that comes into
Qatar through QFC is not
the most important criteria,
QFC’s main purpose, clarifies
Al-Jaida, is to act as an ideal
platform for international
companies who want to
expand their business activi-
ties to Qatar and the region.
One of the huge benefits that
QFC offers its licensed enti-
ties is having its own legal,
regulatory, tax and business
infrastructure, which allows
100% foreign ownership,
unlimited repatriation of
profits, no restriction on the
currency used for trading
and the competitive cor-
porate flat tax rate of 10%
on locally-sourced profits,
which is adjusted for tax
purposes and determined on
the basis of Generally Ac-
cepted Accounting Principles
(IFRS, UK and US GGAP).
Commenting on the transi-
tion from a zero-tax regime
to the levy of tax by QFC
on its licensed firms since
the QFC Law No. 7 of 2005
provided for an initial tax
holiday of three years for
QFC entities (extended,
later, to five years), Al-Jaida
says, “The QFC approach
in respect of tax, which is
unique in the region, is not
to provide companies with
permanent tax holidays or to
market itself as a free zone
or a tax haven. Instead, it
took the option of setting
itself up as a location where
financial services provid-
ers and other businesses
can operate freely onshore
(in Qatar), regionally and
internationally, while being
subject to a transparent, fair
and competitive tax regime.”
Al-Jaida clarifies that the
QFC tax regulations (which
became effective on January
1, 2010) provide for a ter-
ritorial tax system whereby
only locally sourced income
is taxable. “In other words,
income that is derived from
activities performed outside
Qatar is not taxable.” Clari-
fying that the tax imposition
has had its advantages as
opposed to a permanent tax
INNOVATOR
“Recently, Qatar First Bank became the first
Qatari QFC-licensed firm to be listed on the
Qatar Exchange. This and several other local
success stories add to the real impact that
the QFC has on Qatar’s economy.”
www.qfc.qa
Page 21
february 2017 Entrepreneur
21
holiday, Al-Jaida mentions
that the flat tax has made
it possible for any foreign
company’s branch operation
at QFC to offset its corporate
tax against the tax liability
of the company’s head office,
often even in the absence of
a tax treaty. “This is because
the tax law of most devel-
oped countries provide for
unilateral tax credit relief.
This possibility would not
be available if, instead of
corporate tax, QFC entities
were subject to service fees
or other levies,” explains
Al-Jaida.
Another important advan-
tage, according to Al-Jaida,
of being subject to tax in
the QFC is the access to the
benefits and protections
provided by the wide tax
treaty network of the State
of Qatar. He informs that
Qatar has more than 60
effective tax treaties, and
being subject to tax is often
a requirement to get access
to these treaties, particu-
larly now in this post-Base
Erosion and Profit Shifting
era (or BEPS, a project initi-
ated by the Organization of
Economic Development and
Cooperation) to tackle tax
avoidance. Tax treaty ben-
efits include mainly lower
taxation thresholds and
withholding tax rates, avail-
ability of foreign tax credit,
access to the Mutual Agree-
ment Procedure (a dispute
resolution mechanism) and
protection against discrimi-
nation. Al-Jaida adds that
on the back of the Gulf Coop-
eration Council’s decision to
introduce Value Added Tax
(VAT), by its very nature,
being an international treaty,
the agreement introducing
VAT will apply to all com-
panies in Qatar (including
QFC entities) regardless of
any relief or exceptions pro-
vided for, in domestic laws.
“However,” he clarifies, “the
implementation of the tax
still requires the enactment
of a domestic VAT law, which
will stipulate in full the
details. We know that the
Ministry of Finance is work-
ing on this, and is putting in
place appropriate resources
to make the implementation
of the tax a success.”
QFC is not the only finan-
cial centre in the region
within the GCC, with Dubai
International Financial
Centre being the most
proximate, which could
compete with the QFC in at-
tracting international firms.
But Al-Jaida rules out the
idea of QFC competing with
any other regional financial
centre. “Every financial
centre has its own business
model,” he explains. “Thus
we are not in direct competi-
tion with other financial
centres in the region, with
our own model being that
of an onshore platform that
allows licensed companies to
operate freely within Qatar,
and with any other institu-
tion, in any currency. QFC’s
objective is to promote Qatar
both regionally and glob-
ally. Qatar’s Gross Domestic
Product continues to grow
favorably in comparison to
other oil-exporting countries
in the Middle East, and Qa-
tar has maintained its credit
rating, one of the highest in
the world. The strength and
stability of Qatar’s market
makes it an ideal candidate
for businesses looking to ex-
pand to Qatar and beyond.”
QFC started with bringing
in financial services com-
panies into the country and
later expanded to include
management consultancy,
recruitment, sports and
entertainment, engineering,
and claims services. Speak-
ing about the advantages
that this widening of the
types of companies has
brought about, Al-Jaida
lists out three specific eco-
nomic impacts: direct impact
(based on direct business
benefits from the entities
and companies that QFC has
brought into the country);
indirect impacts (from enti-
ties and companies by >>>
more than 30% of our licensed companies
are local; in our conversations with
them, these local firms acknowledge the
QFC’s robust legislation as an important
facilitator in their success as they expand
in Qatar and beyond.”
1. Measure your risks
“While successful
entrepreneurs are often
stereotyped as having an
almost unhealthy appetite for
risk, a risk-loving personality
is certainly not a prerequisite
for becoming a successful
entrepreneur, so weigh your
risks well and don’t let your
passion and belief in your
idea blind you to unnecessary
risk.”
2. Always have a detailed
plan
“An in-depth plan that
fully details how you will
tackle the challenges ahead
is an absolute necessity.
The plan should define the
opportunities for growth,
the mission, the target,
measurable goals and
deadline for each milestone
along the way.”
3. Surround yourself with
the right people
“Knowing people who can be
your mentor or offer strategic
advice is important but
having the right people with
you on the ground is equally
important. Build your staff
with smart, talented, and
driven employees who share
your vision.”
4. Have confidence in your
business idea
“There will always be people
who will criticize you and
your business model. Ignore
the doubters. If you believe
that you have found a good
product or service, then go
for it. Yes, there may be a
few rejections but use these
to improve your business
instead of letting it drag you
down.”
5. Find a healthy work-life
balance
“Running a successful
business requires an
inordinate amount of time
and energy. It is paramount
to find a healthy work-life
balance, even though it can
be a challenge to do so.”
The Executive Summary
Yousuf Mohamed Al-Jaida’s tips for entrepreneurs
Page 22
Entrepreneur february 2017
22
widening the supply chain);
and induced impacts (from
direct and indirect employee
spending benefits). “Howev-
er,” Al-Jaida clarifies, “QFC’s
contribution goes beyond the
economic contribution; the
foreign companies we attract
bring along an additional
human element, high caliber
staff, knowledge and know-
how that contributes to the
growth and diversification
of the local economy and is
transferred to the local popu-
lation, creating a deep talent
pool that, in turn, benefits
the economy as a whole.”
On QFC’s role as a catalyst
to boosting the entrepre-
neurial culture among the
Qatari youth, Al-Jaida opines
that the QFC is instrumental
in opening up the private
sector in Qatar and exhibit-
ing the ‘best in breed’ of a
huge variety of businesses.
Citing examples, Al-Jaida
mentions, “We have, for
example, attracted some of
the biggest management con-
sultancies in the world and
various professional service
firms that are quite new to
the region. A by-product of
having these firms on the
peninsula is the knowledge
and expertise they bring, all
of which will circulate in the
economy and undoubtedly
inspire both the local youth
and industry veterans to
start their own ventures and
widen their aspirations to
go beyond merely seeking
jobs to creating them.” In
addition, towards promoting
the entrepreneurial mind set,
QFC has taken a more struc-
tural approach by investing
in a partnership with the
Qatar Finance and Business
Academy in a number of
educational schemes aimed
at preparing and equipping
the local human capital and
developing the financial
services industry as a key
source of sustainable growth
for its citizens and residents
alike. Training programs
such as “Kawader” and the
“Future CEO Programme”
developed jointly with QFBA
have been designed to rein-
force the development of the
human capital and recognize
the highly skilled human
capital as a foundation for
entrepreneurship, private
sector diversification and
ultimately the prosperity and
sustainability of the Qatari
economy.
The current hydrocarbon
pricing in the international
market, in the opinion of
Al-Jaida, has presented an
opportunity for substantial
growth in market sectors
such as financial and man-
agement consultancies that
are not directly affected by
the fluctuations in the price
of energy. “These sectors are
naturally thriving in the re-
gion as it moves and matures
to more diverse, sustainable,
knowledge-based economies.
The QFC has recently shifted
its strategy to pay more
focus on attracting firms
that will serve its purpose of
helping in diversifying the
economy in line with the
Qatar National Vision 2030.”
In addition to domestic
initiatives, QFC, in 2016 also
launched its Asia Roadshow
which included events in
the UAE, India and Japan.
According to Al-Jaida, “In
Japan and India, we were
provided with an opportunity
to sit down with prominent
Japanese and Indian inves-
tors to discuss investment
prospects in the country, and
get them acquainted with
the support provided by the
QFC to the firms to expand
globally, and eventually lead
to promote the Japanese and
Indian trade and investment
presence in Qatar.” He adds
that as part of this year’s
roadshows, QFC is looking at
Germany, UK, China, Singa-
pore, USA and UAE.
Reflecting on the decade-
long journey that the QFC
has made since its establish-
ment in 2005, Al-Jaida
says, “The most important
of learning throughout our
journey, in my opinion, is the
realization that today’s busi-
ness environment dictates
that our laws, regulations,
policies and strategies are, in
fact, responsive and require
continuous commitment to
evolve and develop them fur-
ther.” With a futuristic tone,
he signs off, “Staying ahead
of the curve is a major re-
sponsibility, which entails a
lot of dedication, hard work,
unconditional investment
and belief in our most impor-
tant asset, human capital, as
keys to success.”
INNOVATOR
“the foreign companies we attract bring
along an additional human element, high
caliber staff, knowledge and know-how
that contributes to the growth and
diversification of the local economy and
is transferred to the local population,
creating a deep talent pool that, in turn,
benefits the economy as a whole.”
Qatar Financial
Centre Authority
CEO Yousuf
Mohamed Al-Jaida
Page 23
The Regional Leaders of
Construction Evolution
Over 25 flourishing years, ACICO Group sustained a sophisticated position in GCC
& the Middle East as the ideal partner for every property owner, regardless to its type,
throughout the entire project’s life cycle, from construction to management.
00965-1888811
ACICO INDUSTRIES CO. (K.S.C) PUBLIC
www.acicogroup.com
Page 24
“At QBIC, we welcome
startups with
potential to grow, and
equip them with the
tools and facilities
they need to reach
new levels and scale
up. Our mission is
to create the next
QAR100 million Qatari
companies.”
Aysha Al Mudahka,
CEO, Qatar Business Incubation Center
INNOVATOR
INNOVATOR
Entrepreneur february 2017
24
Page 25
february 2017 Entrepreneur
25
I
t’s an exciting time to
be an entrepreneur in
this part of the world,”
says Aysha Al Mudahka,
CEO of Qatar Business
Incubation Center (QBIC),
and before you dismiss this
notion of hers as an oft-
repeated trope, know that
she has good reasons to back
it up as well. “We see that
many populations around
the world are aging, while
the Arabic-speaking world
is, I think, about 50% under
the age of 25, and we have a
large, educated, connected
middle class. That’s a factor
in remaining competitive;
we have an advantage there,
we’re young in this part of
the world. None of us knows
what AlphaGo and self-driv-
ing cars are going to mean for
the labor markets in 10 years,
but we do know that the
Arab world is predicted to
witness 7% above the global
average for internet penetra-
tion by 2018, and that’s an
advantage.”
With this being the case, it
should therefore come as no
surprise as to why entrepre-
neurship has been a priority
for the Qatar government for
quite some time now. After
all, according to Al Mudahka,
for over 20 years now, the
state has been striving to
develop a knowledge-based
economy, moving away from
being a rentier state and
developing a solid, booming
private sector. “The country
has built the necessary
infrastructure, fostered edu-
cation, technology, research
and innovation, as well as
many other aspects that sup-
port this ambition,” she says.
“We’re already witnessing
change and development
in various areas, especially
when it comes to education
and personal development.”
Explaining QBIC’s role in the
overall rubric of the govern-
ment’s plans, Al Mudahka
says, “QBIC fits within the
entrepreneurship, startup
development and incubation
aspect of the SME vision
that Qatar Development
Bank (QDB) is executing,
as well as Nama (previ-
ously known as the Social
Development Center)- they
are our founders. At QBIC,
we welcome startups with
potential to grow, and equip
them with the tools and
facilities they need to reach
new levels and scale up.
Our mission is to create the
next QAR100 million Qatari
companies, and to make sure
that they survive the initial
stages of joining the private
sector and eventually grow
into an SME.”
Realizing this mission
will require changes in the
country’s landscape as well,
and Al Mudhahka notes
that there are a number of
reforms taking place in this
regard- for instance, the
Passion as
capital
Aysha Al Mudahka
The CEO of Qatar Business Incubation Center
wants to steer Qatar’s entrepreneurs toward
a more prosperous future
INNOVATOR
By Aparajita Mukherjee
• Works with two groups
of entrepreneurs - those
who have an idea and would
like to turn into a business;
and those with an existing
small-scale startup looking
for support to accelerate
and grow.
• Provides them with free
office spaces, mentoring,
coaching and a chance
to enroll in one of their
flagship programs:
LeanStartup (LSP) or
the LeanScaleup (LSUP)
Program, both which
are based on the “lean”
methodology, initially
founded by Eric Ries.
Also on offer are smart
financing, legal support,
coaching/mentoring and an
equity share.
• Both LSP and LSUP allow
entrepreneurs to partake
without having a business plan,
or specific degrees required to
start a business. It takes the
entrepreneur’s idea, and quickly
transforms it into a tangible
product or service –a Minimum
Viable Product- while being as
cost-efficient as it can, to test
it in the market to see if the
product is needed and wanted
by the target customers.
• Offers entrepreneurs a seed
fund of up to QAR300,000,
which is then turned into equity
shares. If a company requires
additional funds then we refer
them to our founder, QDB, as
they have specially decided
support systems and services
for entrepreneurs.
www.qbic.qa
The modus operandi
How QBIC helps entrepreneurs
>>>
Page 26
Entrepreneur february 2017
26
Ministry of Economy and
Commerce recently launched
a new mobile application
where one can register a
company and manage most
of the official documents
needed. Moreover, 30%
of public tenders, going
forward, will be dedicated
exclusively to SMEs which,
in Al-Mudahka’s opinion, “is
a very strategic approach,
and will ensure that SMEs
and startups can find good
business opportunities and
chances to grow. It’s really a
perfect time for such policy
to be in place, and I hope
to see our entrepreneurs
making use of such support,
which is offered by QDB
through a conference known
as Moushtarayt, aimed at
creating business opportuni-
ties for SMEs and startups.”
From QBIC’s standpoint,
the organization teaches
entrepreneurs a methodol-
ogy that makes it easier for
them to invest less money
and give more time and
commitment to work on a
minimum viable product
(MVP), try and test it in the
market, generate revenue,
and then out of this revenue,
start scaling up slowly. “We
use the lean methodology to
educate startups,” explains
Al Mudahka. “The meth-
odology and the mindset
should be there before we
introduce money. We do
not give them all the money
they need at once; we start
with QAR100,000 for three
months and test what they
do with it, what they do with
activating their company,
what they do with the cus-
tomer validation, and creat-
ing a second MVP.” During
this stage, it can be assessed
if the business can survive
or not. If they succeed, the
business will remain there
for two years, and QBIC will
have them accelerate during
that time. “Therefore, by
the second year, they are
ready to exit the incubator.
They’re always sheltered
under QBIC’s umbrella, and
we end up taking a lot of
their risks for them. This is
why we have a strict evalu-
ation process and regular
milestone meetings.” Al Mu-
dahka reveals that till date,
QBIC has incubated over 50
companies that range from a
variety of different industries
in the past two years. From
a personal standpoint, Al
Mudahka feels a strong
connection with the QBIC
community- she explains
that it’s hard not to feel very
connected with something
one is passionate about, with
a team that brings in inter-
esting ideas for businesses
and how to take the economy
forward. “I’m not really sure
if that’s something to do with
age,” she says. “I feel sure I’m
still going to feel that strong
desire for engagement and
interest in the future when
I’m older. At the same time,
of course, it is great to be
able to stand as an example
for what is possible. If I can
do it, why can’t others?
And indeed others are doing
the same. There are a lot of
young Arab entrepreneurs.”
As for her own career
trajectory, Al Mudahka began
her professional life at Qatar
INNOVATOR
Aysha Al Mudahka,
CEO, QBIC
“QBIC fits within the entrepreneurship,
startup development and incubation aspect
of the SME vision that Qatar Development
Bank (QDB) is executing, as well as Nama
(previously known as the Social Development
Center)- they are our founders.”
Page 27
february 2017 Entrepreneur
27
Financial Center, which
was then working on a new
project aimed at promoting
Qatar globally, as the ulti-
mate upcoming destination
for business investments.
“It was a great learning
experience for me, and I had
the chance to network and
connect with business lead-
ers and influencers.” From
there, the next destination
was to Wharton Business
School of the University of
Pennsylvania, in the US for
an executive course that
lasted for a month, followed
by an internship in one of
the largest insurance broker
companies in New York at
the peak of the financial
crisis in 2008. “It was a very
challenging time for me to
be involved in this sector,
and from my experience, I
decided that insurance was
not the path for me.” But
the stay in New York City
exposed Al Mudahka to a
number of startups –this
included small boutiques,
small projects in the field
of arts, culture, social me-
dia, e-solutions, food and
beverage– which inspired
her to get more involved in
this realm, and she ended
up joining a program at
Carnegie Mellon University
in Qatar (CMUQ), related to
corporate innovation and en-
trepreneurship. “It is at that
stage that I realized my true
calling- to focus on women’s
development in the work-
force, alongside innovation
and entrepreneurship. From
that point, I became more
involved with entrepreneur-
ship. It has been eight years
now that I have been work-
ing in this field, and being
part of its development and
really laying the foundations
for a strong private sector,
has made my career so much
more worthwhile.”
Given her current position
and her career trajectory, it
should come as no surprise
that Al Mudahka is a role
model for many women, and
she doesn’t hesitate from
speaking up for her peers
as well. She sheds light on
a white paper produced by
Education For Employment
in collaboration with
Bayt.com and YouGov en-
titled, First Jobs for Young
Women in the Middle East
and North Africa, which says
that if women’s participa-
tion in labor markets in the
MENA equaled that of men’s,
the regional GDP could rise
by 47% over the next de-
cade, and the MENA region
alone could realize US$600
billion annually in economic
impact (US$2.7 trillion by
2025). “This shows that
there is actually more of
an opportunity for women
to start their own business
than to join the workforce,
because the latter requires
100% commitment,” Al
Mudahka notes. “Unlike a
full-time office job, entre-
preneurship grants women
the opportunity to work
from home, or from a place
of comfort.” She adds that if
we want a smarter economy,
“not merely an economy
trying to play catch-up with
America regarding working
women while America plays
catch-up with Sweden, then
the economy has to reflect
the way we do things here.
It has to be a transformation
taking us towards our own
ideal society, not someone
else’s. The economy is a
function of human interac-
tion and transaction. It is
not separate from culture,
history, religious practice,
society’s expectations,
people’s behavior. All of that
means that women in the
Arabic world can and should
work if they want to.”
It’s clear that Al Mudahka
is thus a firm champion of
entrepreneurship in Qatar,
but given that we live in a
culture where failure is still
considered taboo, I ask her
what she recommends for
people wrestling with this
kind of self-doubt. “Dealing
with failures in public is not
something that is favorable,”
she agrees. “But we are very
blessed to have families that
always protect us -maybe a
little bit too much- in order
for us to take risks, which is
both a blessing and a curse.
As far as entrepreneurship
is concerned, in order to
achieve success, risks need
to be taken and challenges
overcome, and sometimes,
that means you need to fail
and try again.” And that’s
where institutions like QBIC
come into play- Al Mudahka
says she and her team are
there to help people succeed,
and that includes helping
people who may find it dif-
ficult to rise again after a
setback. “Failure is part of
anyone’s lifecycle; it is one
step to move forward and to
become even more success-
ful,” she says. “It is just one
of the lessons that you have
to go through to pick up the
next opportunity, and move
forward. If an entrepreneur
is passionate enough, then
failure will never be the end
of your journey.”
QBIC has partnered with
Qatar Tourism Authority
(QTA) to set up a specialized
incubator called QBIC
Tourism that will enable
entrepreneurs to develop
products and services
to enhance the Qatar
tourism experience, by
providing them with unique
business development
tools and access to insight
and guidance from QTA
decision-makers. “We have
incubated seven companies
so far, and have received
hundreds of applications for
aspiring entrepreneurs,” Al
Mudahka says. “We have
recently partnered with
Ooredoo Qatar, focusing
on digital solutions,” she
adds. “Together, we set
up a specialized incubator
called Digital and Beyond,
which focuses on startups
with digital solutions in a
variety of sectors including:
healthcare, sports, public
services or finance and have
incubated five startups,
with many more ideas and
applicants in the pipeline. We
only launched this project
a few months ago. It has
already gained tremendous
popularity amongst aspiring
entrepreneurs.”
Partnering for progress
QBIC CEO Aysha Al Mudahka on enabling collaborations
to push the SME sector forward
QBIC winning
Startup Hub of
the Year at
Entrepreneur Qatar’s
2016 Enterprise
Agility Awards
Page 28
The entrepreneur’s
HR playbook
[The how-to]
part one
part two
part three
Initiating
innovation
Through the good
and the bad
The (essential) talent
qualifier checklist
Furthering the role of HR in
change management
Securing employee loyalty in the
Middle East
Six tips to guide the hiring
process for your organization
Entrepreneur february 2017
28
A guide to best practices in HR
for all stages of your business
Page 29
february 2017 Entrepreneur
29
The entrepreneur’s
HR playbook
[The how-to]
part one
The (essential) talent
qualifier checklist
Six tips to guide the hiring process for your organization
By Neil Petch
2
1
Put the candidate
on edge. See if
you can make
them squirm by
giving them real
challenges and
tasks to tackle in
the interview.
There comes a time for most entrepreneurs when they consider
–however briefly– the thought of taking on an employee. After all, if
you want your business to grow, if you do want to build something that
leaves a mark on this world, that lifts you up to true entrepreneurial
greatness (and that makes you a rich individual in the process), then
you won’t be getting there alone. A team is needed. You need to build,
and you need to have that “team work” mindset from day one. Hiring
the right people is thus key to your company’s growth- and this means
that you need to pay close attention to how you go about doing just
that. Set aside time and effort to do this right, and rest assured your
startup will be better off because of it.
True entrepreneurs know that the best
way to grow a business is to build a
winning team. That team of talent you
must be constantly building will, after
all, be constantly building your busi-
ness. And so it goes without saying that
the search for those with the “right
stuff” needs to be high up on the busi-
ness owner’s to-do list at any given
time.
But if we are to be honest, talent
building is no easy task. And if we need
evidence of this, there are plenty of
stats out there to illustrate just how
often it can go sideways. For example,
Leadership IQ’s Global Talent Manage-
ment survey quizzed 5,000 hiring man-
agers on their experiences, and found
that a whopping 81% of new hires fall
short of what they were brought on
board to do.
And here’s the thing: a lot of the time,
it is very hard to get a feel for the situa-
tion in advance. If we look to the Lead-
ership IQ study, the main reasons given
for the “falling short” were things like
coachability (unable to learn), lack of
emotional intelligence, lack of motiva-
tion, and temperament. You can do your
best to screen in that job interview, but
the reality is that some of the shortcom-
ings will only be revealed once the hire
is made and the person starts work.
This is not to say you are at the mercy
of it all. Rather, it just means you have
to ensure that your hiring process is
checking the right boxes. And you really
need to succeed here, because part of
the issue with employing someone new
is that if you do get it wrong, by the
time you are aware of the underper-
formance, that person is likely tangled
into your company structure, and “un-
tangling” is often tricky and expensive.
But to be clear, the worst of it is in
fact the missed opportunity costs that
come with not having hired that right
person who would have, by now, already
been serving up wins for you. Indeed,
we want to get this right as often as
we can. And so with that in mind, let’s
take a look at what you entrepreneurs
out there should be considering when
screening to fill any and all positions at
your company.
Be determined to uncover the
fit (or lack thereof) First off,
try and master the ability to spot
the difference between those who
can talk the talk and those who
can truly walk the walk. Job interviews
can get rather social, and so it’s impor-
tant to ensure that as the interviewer,
you don’t forget to come out of the
interview stage knowing that the candi-
date’s skills are suitable for the job– not
simply that they are a nice person.
Pinpoint the essential list of “must-
have” skills for the job, and try and get
real-life examples from the interviewees,
pushing them hard to demonstrate how
they match your needs. Be ruthless here
and press and press until you either
get confirmation or conclude that the
matchup is simply not there.
Should you indeed get confirmation
that this is a potential fit, then move
on to your “would like to have’s.” These
can be soft skills or extras that are not
essential– perhaps a second language, or
just the fact that they are so darn like-
able. Just let them talk a lot and keep
prodding with your well-timed ques-
tions. They are there to prove them-
selves and you must not settle until your
gut tells you that you have screened as
much as you needed to, and that you
have the essential info required about
their ability to meet the specific job
requirements.
Push on the “above and
beyond” We sometimes trans-
fer our own expectations onto
other people and make assump-
tions that they would be happy
and capable of handling the “above and
beyond.” When we do this in the context
of business expectations, that could end
up being a problem. >>>
Page 30
Entrepreneur february 2017
30
They are there to prove themselves
and you must not settle until your
gut tells you that you have screened
as much as you needed to.
The entrepreneur’s
HR playbook
[The how-to]
Neil Petch is the Chairman of Virtugroup. Petch founded Virtuzone in 2009 before launching Virtugroup, a holding company that has a wider
mandate of supporting startups from establishment; to successful market entry; and all the way through to exit. Petch is also the Chairman of
DIFC-regulated GMG, established in 2010 with offices in Dubai, UAE and London, U.K., providing brokerage services for commercial and investment
banks globally. His most recent venture, PrimalMD, was launched in the health sector and focuses on helping doctors addressing the root cause of
illness rather than simply treating the symptoms.
4
5
6
3
Let’s take the publishing world, for
instance, where I spent a great deal
of my career. Doing a bit (or a lot) of
overtime near to deadline is something
that the industry demands. If you have
a monthly publication, for example, it’s
costly to miss a printing slot and every-
one pulls some overtime to hit the date.
So, how willing and able to put in that
overtime is the job candidate sitting in
front of you?
You need to probe. Ask questions like:
“How will you manage working the oc-
casional weekend? Will there be prob-
lems with that?” And do not, for exam-
ple, ask: “Are you willing to...?”, which
is a different kind of question and easier
to answer with a non-committal “yes.”
This is not about forcing people to work
extra hours. Nor is it about trying to
build a company culture where people
feel obliged to work extra hours
out of fear. But for me, that willingness
to go the extra mile at times will always
be a prerequisite for hiring for any posi-
tion.
Put them on edge Testing for
resourcefulness, resilience and
versatility may seem a challeng-
ing prospect. You can try to ask
direct questions to get direct
examples, such as, “Give me an example
of a time you handled a difficult client.”
But best even to take it up a notch. Give
specific tests with a time limit, for exam-
ple– such as the famous sales ability
test where the interviewer produces an
object, and says: “Sell me this.”
The point here –and what is a com-
mon theme for me when it comes to
interviewing in general– is to again push
yourself to uncover the right info. Make
the interview hard on you and the candi-
date, and try and get as practical as pos-
sible. You need to, after all, get a great
deal of clarity if you are to have a real
shot at identifying those who are going
to do the job versus those who are going
to actually help your company grow.
So stay away from the conventional,
and put the candidate on edge. See if
you can make them squirm by giving
them real challenges and tasks to tackle
in the interview. Think these through
well, and plan for them. Even test them
out on existing employees in simulated
interviews to see just what sort of info
they reveal. If you can put someone who
already has the job on edge, then any
candidate who manages the task coolly
is a serious candidate indeed.
Read between the lines for
staying power When look-
ing at someone’s work history
you can see the pattern of their
movement through employ-
ment and to some degree work out their
“employability.” And here you’ll want to
be on the lookout for those that tend to
hop from one job to another without too
much of a care, as that’s a pattern that
rarely changes. Just be aware, though,
that the “hoppers” often do quite a good
job of CV manipulation in order to patch
up those holes, and so you need to make
sure to ask questions to double check if
those timelines are accurate. Quiz them
at length on their experience in the plac-
es they have worked, and straight out
ask them about the timelines and see if
they start to give nervous answers. And
yes, always do check a reference or two.
Now to be fair, some may have moved
from place to place until the point they
landed in your interview chair because
they are ambitious and have been
searching for the right position (and you
may just be serving that up). So don’t
be automatically judgmental. But do red
flag it and use the opportunity to get to
the bottom of someone’s motivation on
the job and whether you feel that your
working environment is a right fit for
them.
Check your role as the hir-
er– what message are you
giving out? This advice is to do
with sending out the right bait to
hook the right fish. To some you
may be selling a “life role,” and that’s
important for you to understand. Before
you even advertise the role, then, define
your hypothetical target personality
and the qualities that person is likely to
have. Once you’ve got that sorted, then
you can sit down and write up the job
proposition in ways that you believe
would appeal to the right person.
Good things happen when you truly
understand and communicate the role
according to such principles. In reality,
though, this is not something that is
done enough in the recruiting process.
It is, rather, too often a case of simply
grabbing the job description template
and filling in a few blanks. But believe
me when I tell you that this lays the
foundation for a successful hiring ini-
tiative and that the extra time upfront
could end up paying off well into the
future.
Take your time Now I’ll leave
you with what is for me always
the best bit of advice to keep
in mind when it comes to the
human resources side of things:
“Hire slowly, but fire quickly.” The point
is of course not to sound harsh. But the
reality is this: if you are going to rush
anything, it should not be the decision
to hire in the first place, because the
fallout from the wrong hire is simply
too expensive, too stressful, and truly
unfair to all involved.
So take your time where possible, and
where not possible, still take your time.
Because what good, after all, is fill-
ing a position quickly when you really
haven’t filled it at all? That is, can we
say the position has actually been filled
if someone unsuitable has been chosen
to fill it? We cannot.
As I mentioned upfront, real entrepre-
neurs know that the best way to grow
a business is to build a winning team.
Which is why real entrepreneurs actu-
ally relish the hiring process despite it
having the potential to be both ex-
tremely time consuming and, yes, even
agonizing on occasion.
But indeed, there can be no corner-
cutting here. It’s that simple. Any
laziness now will only result in more
work for you later. And that logic alone
should be enough for you to never again
settle for anything less than the best
when it comes to the HR effort at your
company.
Page 31
AIM Sponsors and Partners
Host City Partner
Strategic Partner
FDI Report Sponsor
Official Gala Dinner Sponsor
Investment Awards
Sponsor
Silver Sponsor
Knowledge Partners
Official Supporting
Chamber of Commerce &
Industry
Key Media Partners
Official Supporting IPA
Official Courier
Partner
Official Airline
Carrier
Page 32
Entrepreneur february 2017
32
The entrepreneur’s
HR playbook
[The how-to]
infographics © bayt.com
Through
the good
and
the bad
9
part two
By Suhail Al-Masri
Securing employee loyalty
in the Middle East
IN YOUR OPINION, EMPLOYEE LOYALTY MEANS
EMPLOYEE LOYALTY IS MORE THAN THE NUMBER
OF YEARS SPENT AT THE SAME COMPANY
COMPANIES HIGHLY VALUE LOYALTY
33.3%
30.3%
25.3%
11.1%
Maintaining
company
confidentiality even
after resigning
Being dedicated
and abiding to
the company’s
values and rules
Being proactive
and invested in
promoting the
company’s vision
Staying with a
company for
many years
of professionals said that
they are “extremely” or
“very” loyal to the
companies they work at
79.4%
of professionals are
planning to stay with their
current company for at
least 2 years
31%
of employers are
interested in having loyal
employees
76.6%
O
nce you have got the best
people onboard your enter-
prise, it’s then important to
not be complacent about
your employees- doing so
will see you losing your best people,
and we all know that recruiting a new
person will involve a lot of time, ener-
gy and cost, all of which are resources
that startups or SMEs cannot afford
to waste. To retain talent, you need to
secure their loyalty, and that means
you, the entrepreneur at the helm of
the company, need to be consistently
reviewing the work environment that
you are building in your organization.
Remember, employee loyalty is not
something you can be lax about- it is
a key indicator of your startup’s ef-
ficiency, and your likelihood of success
in the long term.
Companies are highly interested in dis-
covering the best practices out there for
securing top talent. Every employer wants
to make sure every new member they
add to the company is able to contribute
positively. But sometimes, companies find
themselves without a clear plan to engage
those employees who have long ago passed
the screening and hiring phases. Namely,
those who have began their months and
years of hard work and dedication, and are
no longer under the spotlight. Some em-
ployees might’ve assimilated so well to the
company culture and work requirement
that it is hard to recall their induction
phase. Others have proven to be extremely
talented and skillful to the extent that
they are taken for granted, which could
cause them to feel neglected or underval-
ued at times. The reality is, it takes just as
much effort to retain top talent as it does
to find them in the first place.
Employee loyalty often comes to focus
around this time of the year. Having
undergone a busy season of perfor-
mance evaluations, feedback, and pos-
sible promotions or salary raises, most
professionals find it now appropriate to
evaluate their career trajectory and to
begin making adjustments as they see fit.
Having said that, employee loyalty is not
a seasonal topic. It is, in fact, one of the
most important indicators of efficient
work environments; it affects individual
performance and often correlates with
overall productivity and healthy work
dynamics. A Bayt.com poll, Employee Loy-
alty in the Middle East and North Africa,
revealed that nearly nine in 10 respond-
ents (88.9%) agree that high employee
loyalty drives more productivity in the
workplace.
Many managers and business leaders
would be happy to hear that 79.4% of
respondents from the Middle East and
North Africa (MENA) said that they are
loyal to their companies. But take that
with a grain of salt: employee loyalty
is not unconditional. There are several
requisites that professionals always
expect to have and there are many areas
that could be enhanced in order to truly
secure employee loyalty. Employee loyalty
can quickly decline if companies stop
listening to their employees and finding
new methods to give them the necessary
career boost.
What employee loyalty really
means
Many companies mistakenly look at only
one element when measuring employee
loyalty. It is easy to get this wrong but
employee loyalty is not synonymous
with retention rate. Surely, with higher
employee attrition loyalty will suffer, but
employee loyalty comprises many more el-
ements. In fact, only 11.1% of profession-
als polled by Bayt.com, the Middle East’s
leading job site, associate the number of
years at a company with loyalty, making it
the least commonly cited one.
Page 33
february 2017 Entrepreneur
33
THE MAJORITY OF PROFESSIONALS ARE SATISFIED
WITH THEIR COMPANY AND ENGAGED AT WORK
THERE SEEMS TO BE A SPLIT ON WHETHER AGE AFFECTS
LOYALTY TO THE COMPANY
BENEFITS OF EMPLOYEE LOYALTY
I AM SATISFIED WITH THE
COMPANY I WORK AT
Do you agree, older generations and more experienced professional are generally
more loyal than fresh grads and millennials?
I AM HIGHLY ENGAGED AT WORK
Strongly
agree
38.8%
Strongly
agree
50.1%
Somewhat
agree
16.5%
Neutral
26.9%
Somewhat
disagree
9.2%
Strongly
disagree
8.6%
Somewhat
agree
40.9%
Neutral
6.2%
Somewhat
disagree
1.2%
Strongly
disagree
1.6%
Strongly
agree
21.1%
Somewhat
agree
26.8%
Neutral
14.4%
Somewhat
disagree
15.3%
Strongly
disagree
22.4%
of professionals believe that loyal employees contribute extensively to the
productivity of the company and towards achieving its goals
88.9%
The entrepreneur’s
HR playbook
[The how-to]
Many companies mistakenly look
at only one element when measuring
employee loyalty. It is easy to get
this wrong but employee loyalty
is not synonymous with retention
rate. Surely, with higher employee
attrition loyalty will suffer, but
employee loyalty comprises many
more elements.
According to the Bayt.com poll, Employee
Loyalty in the Middle East and North
Africa, a third of employees refer to
confidentiality, even after resigning from
a company, as the most vital factor for
being loyal. 30.3% of respondents think
of loyalty as being dedicated and abiding
by the rules and values of the business.
Another quarter (25.3%) define loyalty as
taking initiative and promoting the com-
pany’s vision and interests. Loyalty in the
Middle East entails the aforementioned
definitions and more.
Now is the time that such a compre-
hensive definition and approach towards
employee loyalty are adopted by all com-
panies and organizations in the MENA
region.
Why companies should care
about loyalty
The general consensus among respond-
ents across the MENA region (88.9%)
is that employee loyalty contributes
extensively towards productivity and
towards achieving goals and objectives.
Having such understanding of loyalty
can be transformative for every business.
Employee loyalty is not a microscopic
issue concerning individual workers or
distinct personalities. Employee loyalty
is a company-wide development that can
hugely influence the bottom line. Securing
loyalty is a big endeavor that employers
should aim to implement with the help of
managers, human resource officers, and
all employees.
Other benefits of employee loyalty cited
in the Bayt.com poll, Employee Loyalty
in the Middle East and North Africa,
include higher efficiency (32.1%) and
stronger team relationships and dynam-
ics (30.8%). A quarter of respondents
feel that employee loyalty correlates with
employee satisfaction. 6.2% of respond-
ents suggest that loyalty leads to lower
turnover rates, which in turn means lower
costs spent on sourcing, hiring, onboard-
ing, and training talent.
What influences employee
loyalty
Having recovered a more wide-ranging
definition of employee loyalty, it is no
longer surprising that the factors and ele-
ments that drive loyalty up and down are
varied. Indeed, this is where differences
in personalities and work styles come into
play. Certain employees may be influ-
enced by one factor and not the other.
Nonetheless, there is agreement among
professionals over certain factors. 83.2%
of respondents to the Bayt.com poll,
Employee Loyalty in the Middle East and
North Africa, say that the office and work
environment is an important factor for
fostering loyalty. Without doubt, work en-
vironment is more than architecture and
furniture; it also involves communication,
flexibility, and overall work culture. >>>
Page 34
Entrepreneur february 2017
34
Suhail Al-Masri is the VP of Employer Solutions at Bayt.com. Al-Masri has more than 20 years of experience in sales leadership,
consultative sales, account management, marketing management, and operations management. His mission at Bayt.com goes in line with
the company’s mission to empower people with the tools and knowledge to build their lifestyles of choice.
SO HOW CAN COMPANIES PROMOTE LOYALTY?
of employees say that the office
environment is very important to
their loyalty levels
of professionals disclosed that lack of
promotions or career growth is the
most damaging factor to employee
loyalty
38.2%
83.2%
WHAT DOES EMPLOYEE LOYALTY DEPEND ON?
16.3%
Direct manager
17.4%
Team members
19.1%
Top management
19.2%
Compensation
and benefits
28%
Salaries
The entrepreneur’s
HR playbook
[The how-to]
infographics © bayt.com
Without doubt, work environment
is more than architecture and
furniture; it also involves
communication, flexibility, and
overall work culture.
More than a quarter (28%) of respond-
ents feel that loyalty depends on income.
Others (19.2%) disclosed that loyalty
is dependent on being rewarded. Top
management has also been listed for its
impact on loyalty by 19.1% of respond-
ents, whereas 17.4% believe it’s all about
team members and the people they work
with on regular basis.
How companies can secure em-
ployee loyalty
The answer may sound very simple: em-
ployees want to feel that they are valued,
and that the company is still invested in
them and wants to improve their career
beyond the initial stages of hiring and
on-boarding. The lack of career growth
opportunities was cited as the top reason
for damaging employee loyalty in the
Bayt.com poll, Employee Loyalty in the
Middle East and North Africa. This senti-
ment was also echoed in the 2016 Bayt.
com Career Development in the Middle
East survey. Many employees felt that
their companies are failing to equip them
with the learning and training opportuni-
ties needed to ensure their career growth.
This leaves the employee feeling disad-
vantaged in their jobs. In fact, more than
three quarters of professionals say that
they are ready to leave their company for
better training opportunities. Companies
need to focus on providing training op-
portunities that address their employees’
exact needs and preferences.
Bayt.com, for example, has repeatedly
emphasized providing state-of-the-art
training and support. The Middle East’s
leading job site also cares about foster-
ing a work environment where teamwork
and creativity can flourish and ideas can
be shared freely. As a result, Bayt.com’s
headcount has been growing steadily and
rapidly, their turnover is at a healthy low
level, and they have been awarded the Top
Ten Places to Work in the UAE award for
four consecutive years, the People and
Culture of the Year award (2012), and the
Best Workplaces in Asia list (2015).
Aside from continuous learning and
professional development opportuni-
ties, employees have many expectations
from their companies that would in turn
enhance their loyalty. Fairness in treat-
ment was named the most popular choice
by 22.4% of respondents to the Bayt.com
poll, Employee Loyalty in the Middle East
and North Africa, followed by wanting
credit and rewards for their achieve-
ments by 21.9% of respondents. 18.1% of
polltakers look for a company that helps
them balance between work and life, and
14.5% believe in the importance of strong
relationships with the company and other
employees.
The responsibility of enhancing em-
ployee loyalty partially falls on the shoul-
ders of managers. In their relationships
with their direct managers, employees
want to feel that they matter and that
they are listened to. Four in 10 respond-
ents (40.7%) think that a direct manager
should listen and align the employee goals
with the company goals. More than a
quarter (27.5%) want managers to help
them understand the company’s mission
and values and another 23.9% care about
strengthening their relationships with
management.
Employers in the Middle East and North
Africa should be well aware that granting
opportunities for growth and advance-
ment and truly listening to what matters
to the employee are among the best ways
to win their loyalty and support. Once
again, we are not simply talking about
retention here. Employee loyalty is paral-
lel to dedication, trustworthiness, and
positive work ethics that are of huge value
to every business. Targeting loyalty plays
a central role in furthering the success
strategy of any organization or company,
regardless of size and activity sector.
Keep this in mind: not only does high
employee loyalty translate to higher
productivity and satisfaction, it also reas-
sures employers that their work environ-
ment is of a high caliber and that they are
in a stronger position to keep their highly
valued employees motivated and attract
more top talent in the future.
Page 35
Page 36
Entrepreneur february 2017
36
The entrepreneur’s
HR playbook
[The how-to]
Initiating innovation
PART THREE
By Anton Van Der Walt and Kristofer Kumfert
Furthering the role of HR in change management
Anton Van Der Walt has served as Human Resources Director of Ford Middle East and Africa since May 2014. In this position, Van Der
Walt leads the regional Human Resources functions from organization development and transition supporting the new business unit
establishment, strategic workforce planning and leadership management.
The Ford booth at
the CES show in
Las Vegas,
January 2017
ford ces image © kooby dagan / shutterstock
A
s an entrepreneur running a growing business, you may
think of a dedicated HR department for your company as
being a sort of overhead for your enterprise- but nothing
could be further away from the truth. As the number of
employees in your organization grows, the HR personnel
you have engaged for your team can play an integral role in building
an efficient and effective work culture that inspires and encourages in-
novation in all of your different functions. Don’t believe us? Take a look
at the role the HR team plays at one of the largest companies out there
(and one that stays true to its entrepreneurial beginnings), the Ford
Motor Company. HR professionals at this multinational automaker are
using their positions to help their company gain a competitive advan-
tage in what is a cutthroat market- that’s something you entrepreneurs
should also be striving toward for your own businesses.
A lot has changed in the space of human
resources over the past several decades.
Gone, in large part, are the personnel
departments whose focus was solely
processing of employee pay and benefits.
The hard-fought battles for HR to have the
coveted “seat at the table” have persuaded
organizations to realize the benefits of
enhanced talent selection, employee
engagement, and staffing to appropriate
demand levels to facilitate lean operations.
But the more pressing question for HR
professionals is no longer how to get a seat
at the table, it is how best to use that seat
at the table to be a competitive advantage
for the organization beyond the traditions
of staffing and talent management. To
achieve this, HR needs to embrace in-
novative thinking that takes the skill team
outside of traditional areas of “expertise,”
and into areas of the business where their
skills can be stretched, challenged, and
impactful to the bottom line.
Creating change facilitators
In 2009, Ford Motor Company made a
critical decision to invest in the direction
of its HR professionals. The investment
was part of the company’s organizational
Page 37
february 2017 Entrepreneur
37
Kristofer Kumfert, Human Resources Manager of Ford Middle East and Africa, is responsible for human capital management activities
for the design, development, and implementation of Ford’s newest business unit headquartered in Dubai. Kumfert has been with Ford
for almost 20 years, joining the plant protection team in 1997.
enhanced and sustained business results
structured change management
building process
analyze
First, identify the issue in its entirety, identify a leader to take
charge of a resolution plan, and to identify critical elements such
as desired state, key enablers and roadblocks.
With a solide solution design based on data and rooted in the
originating business care, the team is well-positioned for the
final phase to implement the change.
With a well-defined project plan, the
next phase is to conduct data collection.
Data drives the team to get to the root
of the issues and uncover all relevant
considerations.
Once the data is on the table,
the next step is to make an
informed series of solution
alternative decisions on the
way forward.
identify
1
2
solution
3
implement
4
The entrepreneur’s
HR playbook
[The how-to]
The Ford Motor Company
World Headquarters
building in Dearborn,
Michigan
Strong HR professionals
play a consultative role
and bring their operational
leaders back from
“solutions” mode, and make
sure that appropriate
due diligence is exercised
before any solutions are
activated.
>>>
development model, a system
of tools and processes to
achieve an effective culture
through individual, team, and
organizational effectiveness.
An internal change process was
created to guide the company’s
change management practices.
It was about more than just
helping people through change.
It was about being driven by a
clear business opportunity and
facilitating change through to
improved and sustained busi-
ness results. It was anything
but soft and fluffy. Ford’s HR
leadership, under the direction
of Group Vice President Felicia
Fields, developed a specific
program for HR professionals
to facilitate change manage-
ment throughout the organi-
zation. With over 100 years
of history, the company had
experienced change initiatives
with varying degrees of suc-
cess, and this led to the deci-
sion that HR’s role in managing
change and facilitating the
company’s leadership through
such initiatives would lead to a
competitive advantage for the
organization.
The Ford change model was de-
signed to be simple, practical,
and effective.
• The first step is facilitating
the organization to identify the
issue in its entirety- the issue
we’re trying to solve, the busi-
ness opportunity, the burning
platform. This first phase in-
volves identifying a sponsor for
the change –a leader to be the
owner of the initiative– and
identifying critical elements
like the desired state, as well as
key enablers and roadblocks.
• Once the project is well de-
fined, the next phase is to con-
duct data collection. Too often,
change initiatives are com-
menced when everyone thinks
they know what to do. This
phase is intended to inform the
team’s actions, rather than af-
firm them. The data drives the
team to get to the root of the
issues and uncover all relevant
considerations before design-
ing any solutions.
• Once the data is on the table,
the next step is to make an
informed series of solution
alternative decisions on the
way forward.
• With a solid solution design
based on data and rooted in
the originating business case,
the team is well positioned for
the final phase to implement
the change.
Throughout the entire pro-
cess, the process is governed
by common principles that
include ensuring sponsorship,
communication, surfacing and
overcoming resistance, and
attending to the culture. It is
a disciplined, purposeful, and
effective process to manage
change from a clear business
opportunity through to effec-
tive and sustainable business
results.
The mantra of problem
resolution training at Ford was
“go slow to go fast,” and HR
professionals get a quick lesson
on why that’s so important
and so challenging. While the
model is usually well received
among operating partners
with nodding heads when it is
presented, the data-gathering
phase often tests a team’s com-
mitment to the process. Lead-
ers like solutions. Solutions
fix problems, so any step in
between identifying a problem
and implementing a solu-
tion is often uncomfortable.
Strong HR professionals play
a consultative role and bring
their operational leaders back
from “solutions” mode, and
make sure that appropriate due
diligence is exercised before
any solutions are activated.
The results have been im-
pactful. Staffing, development,
and organizational change ini-
tiatives have all been executed
with demonstrably effective
and sustained results. Train-
ing programs were expanded,
funded, and supported glob-
ally to increase the number
of HR professionals with a
core competency in change
management, demonstrating
a proficiency in supporting
change projects throughout the
organization.
An opportunity to be
innovative
In early 2016, Ford’s newly
formed Middle East and
Africa business unit began to
experience significant market
headwinds. Currency devalua-
tions, falling oil prices, import
quotas, and regional instability
were causing major markets
to make forecast adjustments
that were bleak. There was a
clear need to do something and
deal with the market realities
upfront and aggressively.
The initial response by the
leadership was to come togeth-
er with a list of action recom-
mendations, and then decide
on next steps. The discomfort
of the problem was there, and
everyone wanted to feel at
ease with a series of solutions.
Page 38
Entrepreneur february 2017
38
The entrepreneur’s
HR playbook
[The how-to]
When organizations face chal-
lenging business environments,
HR has some frequent levers to
pull– like staffing, benefits, and
training and development. These
are traditional approaches most
organizations look at in a tough
business environment.
The Ford booth at the CES show
in Las Vegas, January 2017
The Ford Motor
Company display at
the North American
International Auto
Show in January 2017
The theme quickly moved to an all-too-
familiar place surrounded by questions
regarding the best possible cost-effective
practices. All were well intentioned, and
all were tried and done before.
The HR department in Middle East and
Africa was at the table with the leader-
ship team, and identified an opportunity
to provide a different approach. Amongst
themselves, the local HR group discussed
the key message that Ford’s CEO Mark
Fields delivers about being innovative,
questioning traditional actions, and taking
thoughtful risks. That is, when we see an
area that is in need of help, we need to
find ways to come together and provide
whatever support we can to resolve the
issue; we shouldn’t just settle for actions
we’ve traditionally done because that’s
a comfortable space. The opportunity of
mounting market pressures was calling on
the team to be innovative in the role they
played to contribute to the business’ abil-
ity to navigate through tough conditions.
Scarcity leads to creativity
When organizations face challenging busi-
ness environments, HR has some frequent
levers to pull– like staffing, benefits, and
training and development. These are tradi-
tional approaches most organizations look
at in a tough business environment. The
challenge in Middle East and Africa was
that the lean organization structure left
little room for the usual solutions to be ac-
tivated. The scarcity of opportunity to take
actions on staffing and cut costs meant HR
had to embrace a spirit of innovation in
order to help drive the business forward.
As the HR Director for Middle East and
Africa, Anton Van Der Walt was the HR
person at the table, and was
determined to push his HR
team to think different. “I
remember telling my team
that our budget was nowhere
near being significant enough
to trim and cut and make a
sizeable difference, so we had
to do something else.” said
Van Der Walt. “I kept remind-
ing them about our need to be
innovative, and work outside
our usual comfortable areas.
The business needs us, and
we have to find a way to use our skills
in new and creative ways.” The local HR
team in Dubai, together with operational
leadership throughout Middle East and
Africa, met and discussed using the
change process to purposefully guide the
team through identifying, understand-
ing, and researching the issues that could
be considered to contribute to improving
the company’s performance in light of the
business environment challenges. This
was a departure from the usual change
management projects HR undertook that
always had a main theme about a people-
based issue to be solved. This was differ-
ent. The team embraced the innovative
mindset to challenge custom and question
tradition.
After a thorough definition of the busi-
ness opportunity, the HR team facilitated
brainstorming sessions with the broader
leadership team to uncover revenue and
cost opportunities, as well as new busi-
ness actions to leverage untapped business
streams. The team originally came into the
sessions expecting the same focus on cost-
efficiency with which they had become
accustomed over the years, but this was
different. Because the business opportuni-
ty was so well defined as being overall per-
formance and not just cost-focused, the
scope was broadened to include revenue
and new business. With the brainstorm-
ing resulting in over 150 ideas, a core team
met and plotted the ideas against ease of
implementation and expected impact to
the business unit’s performance.
The result was staggering. Through HR-
facilitated sessions in Dubai and South
Africa, the leadership team was able to
identify, action, and deliver significant
cost enhancements that positively impact-
ed the business unit’s performance by mil-
lions of dollars. Moreover, everyone could
feel the excitement. Taking a systematic
approach to the business environment em-
powered people to feel that they were tak-
ing control of their destiny. According to
Middle East and Africa CFO Mike Agosta:
“Without HR, we never would have met
as a team and followed such a process. We
would have spent our time on the usual
cost-related ideas with the usual results.”
The team walked away stronger, smarter,
and closer in large part, because they were
guided by their HR partners through the
change with a solid change framework.
Further evidence of the impact of the HR
change activities was seen in the demand
it created. Business leaders did not know
that HR change management could be
applied to the business in such a man-
ner, and demand for HR’s involvement in
business initiatives to facilitate and guide
operational groups has grown significantly.
Page 39
february 2017 Entrepreneur
39
James Randall is the Regional Sales Manager at HireRight Middle East.
The entrepreneur’s
HR playbook
[The how-to]
Talent tactics
Six tips to improve your candidate’s HR experience- through tech
By James Randall
W
ith technology playing such
an integral part in our lives,
candidates are increasingly
expecting the recruitment process to be a
slick, digital experience- and this demand
is only going to increase. So how can HR
teams stay ahead of the competition,
providing easy-to-use and reliable services
that present your company in the best light,
and so help ensure you attract top talent?
We’ve summarized six of the top tech
issues for HR teams to be thinking about in
order to improve the candidate experience.
1. Integrate For international organizations,
providing a seamless, consistent
recruitment process can be tough. But
technology can certainly help. By ensuring
that all the HR systems you choose can
be integrated, you can save time and,
more importantly, reduce the need for a
candidate to fill in the same information
multiple times. This can lead to real
frustration and raise questions about the
operations of an organization, reducing the
likelihood of a candidate accepting a role.
2. Go mobile An increasing number of
jobseekers are not only looking for jobs
on their mobiles, but also applying for
them through their phone. Employers
need to make sure their career pages are
mobile-responsive and simple to navigate
to ensure that forms are completed as
easily and quickly as possible. A webpage
that times out or crashes could lose hours
of work, and even perhaps the candidate’s
enthusiasm for applying for a role. Not
having this functionality in place can also
raise concerns that a potential employer is
outdated.
3. Utilize your social media Your social
media presence is your organization’s
shop window to potential employees: a
recent Monster and YouGov study found
that 59% of millennials browse a firm’s
website when looking for a new job. It
needs to be up to date then, but can also
be a helpful recruitment tool. Whether it’s
through Twitter hashtags, Facebook pages
advertising roles, or LinkedIn job postings,
there are a number of tools jobseekers
are using to find opportunities beyond
traditional job posting sites.
4. Use technologically advanced
screening systems Background screening
is the final seal of approval in many
recruitment processes, so it’s vital that now
that you have the best people identified,
you keep them engaged. Visibility and
communication are key, so make sure that
you use the most tech-enabled platforms
to ensure that candidates are kept up to
date through personalized portals.
5. Introduce video interviews Having the
capability to carry out video interviews is
a win-win. Clearly, video interviews can
be convenient for busy candidates and
recruiters, with far fewer logistics involved
in setting up than with face-to-face
interviews. But there are more significant
benefits too. For candidates, it opens doors,
giving them the opportunity to apply for
jobs across the world and really explain
why they would be suited for a particular
position. For employers, video interviews
give access to a global pool of talented
people, allows assessment of more people,
more quickly and gives greater insight than
can be achieved through a phone call. In
addition, recordable videos can be shared
with senior decision makers without the
need to sit in on every interview. Hiring
managers can also refer back to recorded
interviews to check facts, limiting the need
for follow up calls or interviews for clarity.
6. Don’t be a robot There’s a lot of talk
around the potential for using tools such
as artificial intelligence during recruitment,
but it is important to remember that
these should supplement HR and hiring
processes, rather than replace them.
Technology benefits exist in tasks such as
checking CVs and applications, as well as
simplifying staff training and onboarding
processes. But recruitment is about culture
and people, so human interaction shouldn’t
be removed entirely. Rather, technology
should be used to supplement processes
to save time for both candidates and
recruiters– freeing up time to focus more
on strategic talent planning.
It was a perfect example of creating
demand by showing the customer some-
thing they didn’t even know they wanted
from HR.
Rethinking “change”
The toughest mindset change for the HR
team in Middle East and Africa was to
challenge their limitations on what kind
of change their framework could address.
Were they limited to changes of people
processes? Were they limited to changes
of the financial impact of people? Were
they limited at all? The team decided
that this was their opportunity to em-
brace the innovative mindset to sustain
the business. After all, facilitating a
room full of business leaders and bring-
ing them back from jumping to solutions
and guiding them through brainstorm-
ing and data diagnosis is not where HR
professionals spend a lot of their time.
But the need was evident, and the team
seized upon the opportunity to expand
the idea of change to include any aspect
of the business in need of facilitated and
purposeful improvement activity.
The human resources profession has
come a long way over the years. Count-
less professionals have tirelessly worked
to earn a seat at the table. Now that
they’re there, the next evolution for
HR leaders is to best make use of that
seat, and leverage HR as a competitive
advantage. As the change management
process at Ford, and its expanded usage
as a tool to improve the business dem-
onstrate, there are ways for HR teams
to engage with and facilitate leadership
throughout the organization in ways
beyond traditional people processes.
Human resources professionals engage
with every department and skill team,
and are uniquely qualified to have
among the most broadened viewpoints.
Traditionally, matters outside of staffing,
benefits, and other people-related issues
were considered the responsibility of
“operations,” and HR people were free to
disengage. Those days are over.
HR’s seat at the table brings more
than the right to a voice at the debate.
It brings the duty to be part of the solu-
tion. It brings the obligation to apply
tools and competencies in innovative
ways. It brings the responsibility to em-
brace the innovation mindset and chal-
lenge the custom and tradition. In doing
so, being innovative delivers a fantastic
rewarding feeling, and incredible results.
Page 40
One fixed monthly payment and peace of mind that your capital expenses will not change.
3 Routine service included
3 Machine warranty protection (3 years)
3 Guaranteed trade-back value
3 CareTrack monitoring (3 years)
* Terms and conditions apply
www.famcointernational.com
WHEEL LOADERS • WHEELED EXCA
starting from
AED 12,120
per month*
Page 41
Packaged with:
3 years Service
3 years Warranty
3 years Financing
AVATORS • CRAWLER EXCAVATORS
Page 42
Entrepreneur february 2017
42
Sharjah Chamber and ShjSEEN host Sharjah Economic
Excellence Network Awards 2016
Boosting business
in pictures
Sharjah Economic
Excellence Network
Awards 2016
The winners
• The Sharjah CSR Award
Hilton Sharjah Hotel
• The Sharjah Green Award
American University of Sharjah and
Sharjah Police Headquarters
• The Sharjah UAE Startup Award
Fikra Design Studio and Bukhash
Brothers
• The Sharjah Entrepreneur Award
Hazaa Al Mansouri and Mohammed
Al Mushrakh
• Sharjah Top 10 Businesses
Awards
Anchor Allied Factory, Kingston
Holdings, Al Mosafer, Zulekha Hospital,
Conmix LTD, Al Ansari Exchange and
Petrofac International
The ShjSEEN
Sharjah Economic
Excellence Network
Awards 2016
Winners of the ShjSEEN
Sharjah Economic Excellence
Network Awards 2016
Hazaa Al Mansouri and
Mohammed Al Mushrakh,
winners of the Sharjah
Entrepreneur Award
category
H.E. Sara Al Madani,
Board member, Sharjah
Chamber and ShjSEEN
speaking at the event
The ShjSEEN
Sharjah Economic
Excellence Network
Awards 2016
images courtesy Sharjah Chamber of Commerce and Industry
T
he Sharjah Cham-
ber of Commerce
and Industry
(SCCI) and the
Sharjah Economic Excel-
lence Network (ShjSEEN)
recognized the contribu-
tions of companies and
business leaders of the
Emirate at the Sharjah
Economic Excellence
Network Awards 2016 held
on January 21, 2017 at
Expo Centre, Sharjah. Held
under patronage of H.H.
Sheikh Sultan bin Moham-
med bin Sultan Al Qasimi,
Crown Prince and Deputy
Ruler of Sharjah, SCCI
honored winners across
business sectors in five cat-
egories. During the event,
H.E. Abdullah Sultan Al
Owais, Chairman of SCCI
and Chairman of the Board
of Trustees of ShjSEEN also
launched a new category
for honoring businesses
under the category of top
10 GCC enterprises. H.E.
Al Owais also encouraged
Sharjah’s business com-
munity “to broaden their
participation” in the future
editions of the award,
which are aimed at promot-
ing corporate governance,
encouraging adoption of
quality standards and eth-
ics, recognizing corporate
social responsibility, and
other skills. H.E. Sara Al
Madani, Board Member of
SCCI and ShjSeen said that
the organization’s key focus
for the year ahead will be
to boost Sharjah’s econom-
ic growth by “highlighting
the Emirate as distinctive
destination for business
and modern living.”
Page 43
Page 44
Entrepreneur february 2017
44
Sennheiser
GSP 350
TECH SHINY | WEBSITE TO WATCH | GEEK | MOBILE TECH | ONLINE ‘TREP | THE FIX
As one would expect, innovation abounded at this year’s edition of Consumer Electronic Show (CES) in Las Vegas-
here are a few of the household tech showcased at CES 2017 that made us sit up and take notice.
Float on
LG Levitating Portable Speaker
Phab 2 Pro Fingerprint
LG Levitating
Portable Speaker
The LG Levitating Portable
Speaker (PJ9) makes a strik-
ing impression when you first
lay eyes on it. It hovers in
place over the accompanying
Levitation Station to deliver
high-quality audio. PJ9 creates
the visual effect of levitating by
using powerful electromagnets
that are housed inside the Levi-
tation Station. This may sound
like a gimmick, but there’s real
technical prowess behind this
design. Levitation gives the
360-degree omnidirectional
speaker its unique trait of being
untouched by any surface or
wires when playing. Its sound
is magnified by deep bass,
courtesy of the subwoofer
embedded inside the Levitation
Station. PJ9 also features Dual
Passive Radiator technology
to reproduce flush mid-range
tones and crisp highs. When its
10-hour battery begins to run
low, the speaker automatically
descends to the Levitation
Station and begins to charge
wirelessly without interruption.
PJ9 is IPX7 compliant, so you
can enjoy it inside and outdoors
as well. For added convenience
and versatility, multipoint
technology enables the speaker
to connect to two Bluetooth
devices simultaneously. Suffice
to say the Levitating Portable
Speaker ushers in a new way
to hear and see your music
stream.
Page 45
february 2017 Entrepreneur
45
#TAMTALKSTECH Tamara Clarke, a former software development professional, is the tech and lifestyle enthusiast behind The Global
Gazette, one of the most active blogs in the Middle East. The Global Gazette has been welcomed and lauded by some of the most
influential tech brands in the region. Clarke’s goal is to inform about technology and how it supports our lifestyles. See her work both in
print regional publications and online on her blog where she discusses everything from how a new gadget improves day-to-day life to
how to coordinate your smartphone accessories. Visit www.theglobalgazette.com and talk to her on Twitter @TamaraClarke.
TECH
SHINY | WEBSITE TO WATCH | GEEK | MOBILE TECH | ONLINE ‘TREP | THE FIX
Beam it
Sony Portable Ultra Short Throw Projector
Stay cool
LG Smart InstaView Refrigerator
Sony Portable
Ultra Short
Throw
Projector
LG Smart InstaView Refrigerator
LG Smart
InstaView
Refrigerator
display
IMAGES COURTESY: LG, SONY
Sony’s Life Space UX
concept offers new ways
to transform your living
space while experiencing
technology. Products like the
Portable Ultra Short Throw
Projector, a tiny projector
that can beam an image onto
any surface from a very short
distance, blends function
and style seamlessly. The
battery powered device
measures 3.19” x 5.16” x
5.16” (81mm x 131mm x
131mm) and can produce an
autofocused image between
20 and 80 inches. You can
enjoy content via the HDMI
input or a wireless hub
connected to your television
or computer. It also features
Bluetooth Low Energy,
which allows you to stream
from nearby Bluetooth
enabled devices like a
smartphone. And here’s
where the stylish element
comes in- the Portable
Ultra Short Throw Projector
can sit atop an optional
stand. With the stand, the
Projector looks like a minimal
piece of modern furniture
accenting your living space.
This small -and I do mean
small- addition to your space
improves both aesthetics and
your multimedia experience.
LG introduced a new kind
of refrigerator called Smart
InstaView at CES 2017,
and let’s just say that it’s
not your average kitchen
appliance. Smart InstaView
is embedded with an array
of features and technology
to include Amazon’s Alexa
Voice Service and LG’s own
webOS smart platform. The
Door-in-Door refrigerator
has a 29-inch touch LCD
display, which, thanks
to the InstaView feature,
becomes transparent when
you knock on the screen
twice, thereby allowing you
to look inside the refrigerator
without opening the door.
With webOS, you can enjoy
a host of WiFi-enabled
features directly on the
refrigerator. Amazon’s
Alexa Voice Service gives
you access to an intelligent
personal assistant that can
search recipes, play music,
add items to a shopping
list and place Prime-eligible
orders from Amazon.com
including groceries. Smart
InstaView also serves a
communication hub for the
whole family. The Smart Tag
menu allows you to input the
expiration date of each item
so the refrigerator can issue
reminders when foods near
expiration. Family members
can set up memos for each
other and create to-do lists
that display on the screen.
Have you ever arrived home
after grocery shopping
only to realize you need
five more things? Fret no
more. Smart InstaView has
a 2.0 megapixel panoramic
super-wide-lens camera that
captures images inside the
fridge that are accessible
via a smartphone. From
food storage to family
communication to smart
shopping, Smart InstaView
has got you covered.
Page 46
Entrepreneur february 2017
46
business unusual | LIFE | TRAVEL | DESIGN | TRAPPINGS
CULTURE
WATCH OUT
‘Trep trimmings
The executive selection
H. MOSER & CIE
F
rom better goods to better wardrobe bests, every issue, we choose a
few items that make the approved executive selection list. In this issue,
we are presenting our picks in timepieces to adorn your wrist- and yes,
we’ve got a variety to styles (and brands) to choose from.
Entrepreneur january 2017
46
H. Moser & Cie
Venturer Tourbillon
Dual Time
If you’re looking for practicality
with a prestigious touch as a
tourbillon, look no further. H.
Moser & Cie has the watch for
you with the H. Moser & Cie
Venturer Tourbillon Dual Time.
Featuring the first tourbillion-
based movement offered by the
Swiss watchmaker, it also pays
homage to its 1960s design and
Bauhaus influence. Rich in tone
and texture thanks to a light
sunburst pattern, the two-time
zone watch’s collection offers
ardoise, silver and red-gold style.
Combining old school vibe and
function, it’s one you should be
keen to watch out for.
www.h-moser.com
Page 47
february 2017 Entrepreneur
47
Images courtesy h. moser & cie, carl f. bucherer, tag heuer, rado
business unusual | LIFE | TRAVEL | DESIGN | TRAPPINGS CULTURE
Editor’s pick
GAME, SET, MATCH
RADO
Swiss watchmaker Rado’s love
for tennis has been steadfast
over the years, and the new Rado
HyperChrome Match Point is a sign
of the horologist’s dedication to the
sport. Building on the classy look and
feel of the erstwhile HyperChrome
Match Point, this limited edition
timepiece’s nod to tennis can be seen
in its three sub-dials- besides the net-
like pattern on the hour counter, the
seconds counter and the chronograph
minutes counter display digits,
characteristic of points in tennis.
www.rado.com
HITTING THE BIG TIME
TAG HEUER
A collaboration between TAG Heuer
and the Carrera Calibre 16 resulted in
the TAG Heuer Carrera Caliber 16 Day-
Date Chronograph Black Titanium
watch. The lightweight piece features
large minute indexes than usual for
wearers who like to live life by the
minute, as well as a titanium finish
with a black PVD coating topped with
a black ceramic bezel. Combining
sleek black and vintage beige, there’s
something nomadic about it, and we
quite like the edge.
www.tagheuer.com
TAG Heuer
Carrera Caliber
16 Day-Date
Chronograph
Black Titanium
Carl F.
Bucherer
Manero
Flyback in
rose gold
Rado HyperChrome Match Point
For ‘treps who like timepieces that
boasts of both prime style and powerful
performance, then the Carl F. Bucherer
Manero Flyback in rose gold may be
right up your alley. Revved up for
Baselworld 2016, the brand introduces
the new Manero chronograph-
promising (and delivering) technical
distinction, thanks to its fascinating
flyback function, of course. A nod to its
classic case in 18K rose gold, complete
with a champagne-colored dial, endows
this timepiece with incomparable
refinement and modernity.
www.carl-f-bucherer.com
DISTINCTIVE DESIGN
CARL F. BUCHERER
Carl F.
Bucherer
Manero
Flyback in
rose gold
Page 48
Entrepreneur february 2017
48
TREPONOMICS
ETHICS | ESQUIRE GUY | SKILLSET | MARKETING | PRO
You’re not using the phone enough-
and it’s a problem
The Esquire Guy wants you to stop only texting and emailing
By Ross McCammon
The telephone perfectly
illustrates a key truth: if you
go to a lot of trouble to get
yourself in a situation that
feels a little uncomfortable
and half-baked and no one
likes all that much, then you
have no choice but to get
yourself out of that situation.
You’re invested. You’ve made an
effort. You’ve prepared.
The next time you’re about to
email or text someone, ask yourself
this: Am I avoiding the phone because
I don’t want to be told “No”? Am I
avoiding the phone because I don’t
want to feel rejection? Is this about
trepidation?
Hey, wanna feel old? Great. Let
me a get a startup exec on the phone.
[Ring, ring] Hi there. I’m trying
to reach Elena Gorman, product
marketing lead at HipChat, the
group chat and file sharing company.
[Waiting] Elena, hello! Question for
you: What do you think of when I say
the word telephone?
“Working in Silicon Valley, I
haven’t had a desk with a phone on
it since 2010.”
You don’t say?
“I can imagine a scenario where get-
ting someone on the phone would
be the quickest way to resolve a
complex issue. But even with that,
we have video chat and group video
chat in HipChat. The only reason to
ever bring up my phone is if Wi-Fi
is spotty. I think most young people
probably associate telephone com-
munications at work with interviews
or more high-pressure situations. In
Silicon Valley, we all work at com-
puters, right? And most of our jobs
are based around using the internet
in some way. To use a phone takes
me physically out of my workflow.
Just the manual process of dialing
with my fingers, looking up a num-
ber…”
Excellent. I’d like to spend the
rest of this column unpacking
pretty much everything she just said.
Thanks, Elena. Elena?
(I think she hung up.)
Elena Gorman has hit on the ironic
value of telephonic communica-
tion. It is fear-inducing (especially
to a generation of texters) because
it involves stakes. Getting on the
phone with someone means a deci-
sion needs to be made. You don’t
go to all the trouble to press seven
to 10 buttons, then listen to two or
three buzzes, then (possibly) speak
to someone you can’t see and not be
here to get something done.
But this is why it works. This is
why it matters. This is why I’m here
to endorse the telephone as the most
valuable form of communication in
business.
First, it’s important to acknowledge
the various ways in which the phone
is god-awful. To begin with, it’s not
a sure thing. (Will the other person
even pick up?) It can be really inef-
ficient. (Phone tag.) It’s strangely
anxiety-producing. (Ring. [pulse rate
creeps up] Ring. [pulse rate creeps
up]) There’s the annoyance of cell-
phone lag. (There’s the annoyance
of… Oh, sorry, you go ahead.) And
there’s the thing where the other
person is eating what has to be a
salad with lots of blue cheese dress-
ing and it just sounds gross.
“My students under no circum-
stances want to make a phone call
to set an appointment,” says Keri
K. Stephens, associate professor of
communication at the University
of Texas, who is writing a book on
communication in business. “I have
an assignment in a class where they
have to do that, and they will make
up every excuse in the book- ‘Oh, I
sent them an email! Oh, I sent them
a text!’ I tell them, ‘No, you have to
talk in real time to another human
being.’ And they don’t want to do it.”
But why? Stephens blames the fear
of rejection: “Some people really
don’t want to bother other people.
But part of the reason is they don’t
want to be told ‘No.’”
And yet this is why the telephone
is the best. It’s better than texting.
It’s better than email. It’s better than
videoconferencing (which, OK, is like
the phone, except with the added
unnecessary worry about what
you look like). It’s the best form of
communication in business pre-
cisely because it kind of blows. The
Page 49
february 2017 Entrepreneur
49
This isn’t going to be about
efficiency. Sometimes the phone is a
more efficient way to communicate
than email, and sometimes it isn’t.
If two people leave a dozen
messages on each other’s voice
mail, that’s a lot less efficient than
sending a single e-mail and reading
a reply to it.
No, this isn’t going to be about
how telephonic communication
helps you work faster. This is
about how the phone makes you
work better. Because unlike e-mail,
the phone forces you to be more
emphatic, more accurate, more
honest.
Tell that to a neuroscientist,
and before you’ve even finished
the sentence he’ll start laughing-
at what you’re saying, and
the accompanying emotional
gradients. What, you’re not aware
of emotional gradients? You have
tons of them, and you’re constantly
communicating them to people- but
only when you speak, not when you
write.
“We’re picking up and processing
heard information within 50
milliseconds of someone speaking.
A lot of this information doesn’t
get processed at a cognitive level,”
says Seth Horowitz, an auditory
neuroscientist. “Some of the first
targets for heard information are
emotional substrates, so [when]
listening to someone’s voice, you’re
picking up emotional gradients from
them.”
Joe Huff, co-founder of Los
Angeles-based LSTN Headphones,
which partners with a nonprofit that
provides hearing aids to people in
need, is –obviously- a believer in the
power of voice.
“There have been so many times,
a new store or account or potential
press relationship, we’ve gotten
on the phone with them and after
the conversation, even [after] just
a 15-minute story about what we
do and why, they say, ‘Wow, I read
everything on your website, but
to hear you tell it, there’s a huge
difference.’ Because we have a
passion-based business, it’s really
important for us to get that across.”
This happens all the time in
business. Yet we are still wary of
picking up the phone. We don’t want
to bother people. We think they
don’t want to talk. And maybe they
don’t. But you’re not ever going to
find that out through e-mail. You’ll
find it out on the phone. If they
stammer, hedge and pause, then you
have valuable information. Maybe
not the information you were looking
for, but valuable info nonetheless.
Why a phone call is better than an email
(usually)
Unlike e-mail, the phone forces you to be more emphatic,
more accurate, more honest
See this article in its entirety at Entrepreneur.com
telephone perfectly illustrates a key
truth: if you go to a lot of trouble to
get yourself in a situation that feels a
little uncomfortable and half-baked
and no one likes all that much, then
you have no choice but to get yourself
out of that situation. You’re invested.
You’ve made an effort. You’ve pre-
pared. You’ve steeled yourself for the
problems that come with talking on
the phone. You’re ready to deal with
an awkward silence. You’re ready to
be on.
The telephone builds grit. And
when the going gets tough, grit comes
in handy.
The next time you’re about to email
or text someone, ask yourself this: am
I avoiding the phone because I don’t
want to be told “No”? Am I avoiding
the phone because I don’t want to
feel rejection? Is this about trepida-
tion?
And while we’re at it, here are some
more questions to consider: am I
avoiding the phone because I don’t
want to make the other person un-
comfortable? Am I unsure of my own
level of commitment to what I want
to propose to the other party? Is it
advantageous to have no written re-
cord of what we’re about to discuss?
Am I in my 20s and unclear about the
nature of this strange piece of equip-
ment on my desk that has numbers
and lights on it and what looks to be
a “cord” of some sort?
If you answered yes to any of those
questions, then call. The telephone
allows you to efficiently converse, un-
like email or text. It allows you to roll
your eyes, unlike videoconferencing.
Most important, it forces you to
be slightly more committed to your
cause. To be slightly more hopeful.
Go ahead; pick up the phone. Say, “Hi
there! I’m invested in this!”
Right?
Hello?
I think you have the wrong number.
Ugh.
Page 50
Entrepreneur february 2017
50
How the “Paper Clip Strategy” can help you
not procrastinate on your goals
By James Clear
Making good habits stick
James Clear writes at JamesClear.com, where he uses behavior science to share ideas for mastering your habits, improving your
health, and increasing your creativity. To get useful ideas on improving your mental and physical performance, join his free newsletter
JamesClear.com/newsletter. To have James speak at your entrepreneurial event contact him jamesClear.com/contact
CULTURE
business unusual | LIFE | TRAVEL | DESIGN | TRAPPINGS
“Every morning,
I would start
with 120 paper
clips in one jar,
and I would keep
dialing the phone
until I had moved
them all to the
second jar.”
Trent Dyrsmid
the entire strategy will
cost you less than $10.
Grab a box of standard
paper clips, get two
standard paper clip
holders, pick your habit
and start moving those
bad boys from one side
to the other.
I
n 1993, a bank in Ab-
botsford, Canada hired a
23-year-old stockbroker
named Trent Dyrsmid.
Dyrsmid was a rookie, so
nobody at the firm expected
too much of his performance.
Moreover, Abbotsford was
still a relatively small suburb
back then, tucked away
in the shadow of nearby
Vancouver where most of the
big business deals were be-
ing made. The first popular
email services like AOL and
Hotmail wouldn’t arrive for
another two or three years.
Geography still played a large
role in business success, and
Abbotsford wasn’t exactly
the home of blockbuster
deals. And yet, despite his
disadvantages, Dyrsmid
made immediate progress as
a stockbroker, thanks to a
simple and relentless habit
that he used each day. On his
desk, he placed two jars. One
was filled with 120 paper
clips. The other was empty.
This is when the habit
started. “Every morning, I
would start with 120 paper
clips in one jar, and I would
keep dialing the phone until
I had moved them all to the
second jar,” he said.
And that was it. 120 calls per
day. One paper clip at a time.
Within 18 months, Dyrs-
mid’s book of business grew
to US$5 million in assets.
By age 24, he was mak-
ing $75,000. Within a few
years, outside firms began
recruiting him because of
his success, and he landed a
$200,000 job with another
company.
Habits that stick vs.
habits that fail
When I asked Dyrsmid about
the details of his habit, he
simply said, “I would start
calling at 8 a.m. every day. I
never looked at stock quotes
or analyst research. I also
never read the newspaper
for the entire time. If the
news was really important,
it would find me from other
ways.”
Trent Dyrsmid’s story is
evidence of a simple truth:
success is often a result of
committing to the funda-
mentals over and over again.
Compare Trent’s results to
where you and I often find
ourselves. We want to be
consistent with our work-
outs, but struggle to make it
into the gym. We know we
should write more thank you
notes, or eat healthier meals,
or read more books, but can’t
seem to find the motivation
to get it done. We’d like to
achieve our goals, but still
procrastinate on them.
What makes the differ-
ence? Why do some habits
stick while other fail? Why
did Trent’s paper clip habit
work so well and what can
we learn from it?
The power of a visual cue
I believe the “Paper Clip
Strategy” works particularly
well because it creates a
visual trigger that can help
motivate you to perform a
habit with more consistency.
Here are a few reasons visual
cues work well for building
new habits.
Visual cues remind you
to start a behavior. We
often lie to ourselves about
our ability to remember
to perform a new habit.
(“I’m going to start eating
healthier. For real this
time.”) A few days later,
however, the motivation
fades and the busyness of
life begins to take over again.
Hoping you will simply
remember to do a new
habit is usually a recipe for
failure. This is why a visual
Page 51
february 2017 Entrepreneur
51
Q What are your do’s and
don’ts for up and coming
fashion startups trying to
grow their brands?
A “Always stay true to the
company vision while having
a clear understanding of the
market, competitors, and
target audience. Make sure
the brand has a signature
that is visible throughout
the products, this way you
are recognized immediately.
We call our significant detail
the Kristina Fidelskaya DNA,
which is our bold silhouettes
and feminine designs. Have an
understanding that in growing
a luxury fashion brand the
business aspect is equally
important as the creative
aspect. They have to join
hands in order to grow and be
successful.
As for don’ts: don’t be
overconfident. Listen to all the
advice you can get because
every point of view can be
a powerful tool. Critics may
feel harsh, but everything
enables you to grow and
build a stronger brand. Don’t
restrict the way you think and
follow the obvious path. By
thinking outside of the box
and pioneering, you can come
up with new creative ways of
launching a new idea. Don’t
be afraid to reach out to your
team. Employing a talented
staff will help you meet
deadlines, bounce ideas, and
collectively create something
more than you would by
yourself.”
Q What would you say is the
region’s biggest challenge for
entrepreneurs?
A “The pace is very fast in
the MENA region, especially
in the UAE. There is a lot
of opportunity and a lot of
investment. The speed of
bringing product to market
is more important than ever,
[and] for young entrepreneurs,
this can be a challenge.
Recruitment can be challenging
as well, as there is so much
talent waiting to be found and
bursting with creative ideas.
But a lot of multinational
companies are here as well,
[so] an entrepreneur needs the
top talent of the region, just as
much as these multinationals,
and [they have to thus]
convince candidates that their
vacancy is the best choice for
him/her.”
Q What’s your advice for
entrepreneurs starting a
business in MENA?
A “Do not set yourself with
too many limitations. Be
experimental, be brave enough
to take calculated risk. Be
ready for a fast paced fashion
lifestyle.”
‘TREP TALK
THE BUSINESS Kristina Fidelskaya www.kristinafidelskaya.com
THE ‘TREP Founder Kristina Fidelskaya
Trent Dyrsmid’s story
is evidence of a simple
truth: success is often
a result of committing
to the fundamentals
over and over again.
Compare Trent’s results
to where you and I often
find ourselves.
Kristina
Fidelskaya
stimulus, like a bin full of
paper clips, can be so useful.
It is much easier to stick
with good habits when your
environment nudges you in
the right direction.
Visual cues display
your progress on a
behavior. Everyone knows
consistency is an essential
component of success, but
few people actually measure
how consistent they are in
real life. The “Paper Clip
Strategy” avoids that pitfall
because it is a built-in
measuring system. One look
at your paper clips and you
immediately have a measure
of your progress.
Visual cues can have
an additive effect on
motivation. As the visual
evidence of your progress
mounts, it is natural to
become more motivated
to continue the habit.
The more paperclips you
place in the bin, the more
motivated you will become
to finish the task. There
are a variety of popular
behavioral economics
studies that refer to this
as the Endowed Progress
Effect, which essentially
says we place more value on
things once we have them.
In other words, the more
paper clips you move to the
“Completed” bin, the more
valuable completing the
habit becomes to you.
Visual cues can be used
to drive short-term and
long-term motivation.
The “Paper Clip Strategy”
can provide daily motivation,
but you start from scratch
each day. However, another
type of visual cue can be
used to showcase your
consistency over longer
periods of time. By stacking
these two methods together,
you can create a set of visual
cues that motivate and
measure your habits over the
short run and the long run.
Creating your own “Paper
Clip Strategy”
There are all sorts of ways to
use the paper clip habit for
your own goals.
• Hoping to do 100 pushups
each day? Start with 10 pa-
per clips and move one over
each time you drop down
and do a set of 10 throughout
the day.
• Need to send 25 sales
emails every day? Start with
25 paper clips and toss one
to the other side each time
you press Send.
• Want to drink 8 glasses of
water each day? Start with
8 paper clips and slide one
over each time you finish a
glass.
• Not sure if you’re taking
your medication three times
per day? Set 3 paper clips
out and flip one into the bin
each time you swallow your
pills.
Best of all, the entire strat-
egy will cost you less than
$10. Grab a box of standard
paper clips, get two standard
paper clip holders, pick your
habit and start moving those
bad boys from one side to
the other.
Trent Dyrsmid decided
that success in his field
came down to one core task:
making more sales calls. He
discovered that mastering
the fundamentals is what
makes the difference.
The same is true for your
goals. There is no secret
sauce. There is no magic
bullet. Good habits are the
magic bullet.
Page 52
Entrepreneur february 2017
52
Liam Farrell is Unisono’s Founding Partner and Executive Creative Director. The branding firm Liam started back in 2006 is the only branding practice
in the entire Middle East to be inaugurated into the REBRAND Hall of Fame. Liam is probably the region’s most highly awarded branding designer
with a slew of international branding awards from notable creative shows such as REBRAND, Transform, Design & Design and the German Design
Council. As well as his awards, Liam’s work regularly features in online branding blogs, design books and archives. Liam is also currently the strategic
communications sponsor for EO Bahrain.
Lost in translation
Communication, multiculturalism and the Middle East
By Liam Farrell
CULTURE
business unusual | LIFE | TRAVEL | DESIGN | TRAPPINGS
C
lear communication
is essential to good
business practice,
and yet so many
Middle Eastern firms
suffer from what we can call
the “fog of war.” What is this,
how can we spot it early on,
and what can we do to prevent
it causing poor performance in
our business?
Let me begin by recounting a
story of the blue stripes.
One day, in my business,
I was briefing my produc-
tion manager on the striped
frosting I wanted applied to
our conference room. To make
matters easier, I drafted the
design as a schematic, and as
a further visual aid, I colored
the glass in a blue gradient,
and the frosting was in semi
opaque white stripes over the
blue gradient -a similitude to
the final finished frosting- or
so I thought.
I sat with the production
manager, and discussed where
I wanted the frosting and ex-
plained my illustrative draw-
ing, pointing to the scale and
touching the glass wall of the
conference room to point out
the positioning of the frosting
versus the picture. From our
conversation, I felt assured the
glass would be frosted as per
my specification.
After a few further update
meetings in which we had
discussed the frosting pro-
ject (design, scale, supplier
estimates, fit out scheduling
and final approved quote), my
production manager said the
“blue stripes will look great.”
I asked him to explain what he
meant by “blue stripes,” and
after a head-in-hands moment
and a few OMGs, I finally
managed to get my production
manager to understand my
briefing, and what my image
was illustrating.
I was thus taught a very use-
ful lesson in Middle Eastern
comprehension: take nothing
for granted. Ever. Ironically,
one of the first things that
become quite clear when you
start working in the Middle
East is just how much confu-
sion surrounds everyone in the
work place. Uncertainty seems
to cloud every day and almost
every decision. In your first
business in the Middle East,
you may think that it’s just
your company that’s riddled
with confusion, but then you
start a second, and a third, and
before long, you recount how
almost every interaction in the
Gulf is tinged with uncer-
tainty, misdirection, or total
confusion.
For everyone in the region,
this must be a frustration: for
clients, an annoyance, and for
business leaders, a real cause
for concern. Getting a coffee
order wrong or missing a dish
from your starter course is a
daily frustration we can all
deal with, but for an entrepre-
neur, trying to get and then
keep a firm off the ground,
daily confusion is a real cost
business leaders can ill afford.
Linguistics is clearly a key fac-
tor in regional miscomprehen-
sion. An insight we discovered
is almost everyone in the
Middle East is talking to each
other in a foreign language.
While English is the common
tongue and de facto busi-
ness language, actual native
speakers are few. Everyone’s
comprehension is subject to
translation, every order and
instruction is being translated,
and a lot can go wrong. For an
illustration of the issues with
comprehension, try to share
a 13-digit telephone number
with someone else. How many
times does it take to get it
right? Simple specifics like
a telephone number or email
address typically require a
few goes to get right. Expand
this situation to your detailed
and specific brief, and you can
begin to imagine how little
comprehension should be
expected between people of
the same tongue- now, add in
a translation.
They say people hear but
rarely listen, and this can be
true here as much as any-
where. Listening is key to com-
prehension. Experts believe
that humans comprehend bet-
ter if they have heard the mes-
sage before- hence why good
presenters sum up. A lot of
people use monologue rather
than real dialogue when talk-
ing to their teams- hammering
their message at an indifferent
recipient, instead of engaging
them in a two-way discussion.
Active listening massively
enhances comprehension. You
need your message’s recipient
to be actively engaged in your
communication for them to
be able to comprehend your
instruction or request. Asking
your recipient to repeat what
you say is also just repeti-
tion, not comprehension. It’s
Page 53
february 2017 Entrepreneur
53
I
t was a year ago, in January 2016, when
the World Economic Forum released The
Future of Jobs report that analyzed the
possible impact of the “Fourth Industrial
Revolution” on global labor markets. The
study stated that the global workforce
needs to brace for significant churn in
job roles, as “a net employment impact
of more than 5.1 million jobs” worldwide
could be seen over the period 2015-2020.
If you think that just factory/blue-collar
workers need to worry about the advent
of robots, the study also noted that two-
thirds of this job loss could be “in routine
white-collar office functions.” It’s just
been a year since this study, and perhaps
worryingly, a few key findings are already
taking shape.
According to Japanese national daily The
Manichi, Japanese insurance company
Fukoku Mutual Life Insurance is planning
to lay off nearly 30% of its assessment
department staff and replace them with
an artificial intelligence (AI) system. The
publication reports that in total, 34 people
are likely to be made redundant by March
2017, and the company will spend “about
200 million yen” to install the AI system,
“which is based on” IBM’s Watson. As
for the benefits, the company estimates
savings of about 140 million yen annually
by trimming down staff, and improved
efficiency in tasks such as reading medical
certificates and other documents assessed
to make payouts. While the authority to
determine payouts will be retained with
human staff, the system is expected to
help scan for special clauses or oversights.
This is not the first instance of use of AI
among Japanese business houses. Per-
haps owing to its population demograph-
ics (largely ageing workforce), and being
leaders in adoption of advanced futuristic
tech, Japan has already implemented use
of AI and robotics in its industries. The
Manichi counts Dai-Ichi Life Insurance and
Japan Post Insurance as other insurance
companies that have already introduced AI
systems, although there are no reports of
staff cuts.
Rise of the machines (really)
AI is taking the place of a few employees at a Japanese
insurance company
| the fix |
more effective to ask your recipient
to explain what they are going to do,
based on the instruction, in their own
words. Then you will know they have
fully understood and internalized your
communication.
Multiply these cultural and linguis-
tic issues together, and you have the
causation of some fantastic misalign-
ment. We can begin to understand
why business leaders in the Middle
East often complain that they are not
understood by their teams. So is there
a remedy leaders can rely on? Is there
a way through the miasma? Well, we
have realized a few solutions and offer
up this simple checklist for reducing
confusion in your business.
• Firstly, lower your expectations of
comprehension. If your recipient can
grasp three out of five of your instruc-
tions accurately the first time, then you
are doing well. Brief in and check up
often. It’s not so much micro manage-
ment, as the frequent steerage of an
eternal beta.
• Make it a point to consider the cul-
tural etiquette of your recipient, and
how they deal with miscomprehension
of a senior’s instructions.
• Remember that we are all communi-
cating in a foreign language, so use sim-
ple, idiom free language. Explain what
you mean in different ways. If you need
to use troubling words, explain what
they mean, and get the recipient to own
their understanding of those terms.
• Get your team to repeat your message
in their own words, to explain what you
meant rather than just blindly repeat
your request and then “debrief and
debrief” until they can clearly compre-
hend all your points correctly in ways
which are meaningful to them.
• Remind your team that it’s ok not
to understand and get your people
to practice saying “I’m sorry, I didn’t
fully understand that last bit; can you
rephrase it for me”?
• If all else fails, don’t deviate from
the items on the menu- just point and
smile!
Page 54
Page 55
Page 56
Entrepreneur february 2017
56
Five financial elements your business needs
to get right- and thus gain a competitive
advantage in the market
By Dr. Christiane Schloderer and Heather Henyon
Money
matters
money ask the money guy | vc viewpoint | your money | ECON
Entrepreneur february 2017
56
T
o borrow from Charles Dickens, it was, at
one point, the “best of times” for this com-
pany that we shall call XSOFT, a promis-
ing software startup. XSOFT had US$2 million
in the bank from an equity investment funding
round the prior year, a super motivated team of
20 people that were running in full force, and a
slew of various awards that were a testament to
its prowess and potential. In terms of finances,
the cash was there, they believed it would last
them until next summer, and revenues should
kick in by springtime. With this picture in mind,
the COO made rough financial projections which
he updated every now and then, the bookkeeper
entered the spend month by month, and the team
continued to happily code. The product seemed to
be making progress as well, with first sales being
made on the platform.
Page 57
february 2017 Entrepreneur
57
A well driven budgeting process
has three elements: it allows
flexibility once the world
around the company changes, it
is reasonably timed, and it also
aligns the departments of the
business to the same company
objectives.
And then, disaster struck: the soft-
ware development team lead said he
would need four more weeks to debug
the product’s latest feature. The CEO
thought, well, that’s bad, but four
weeks is not the end of the world. But
then, the next day, the bookkeeper
called. He wanted to make payroll
payment; however, the bank balance
was almost down to zero. He also
mentioned that most customers had
delayed their payments, asking for
proper invoices, which XSOFT had
not yet provided. Cut to three months
later, and almost all of the team were
gone, the CEO spent most of his time
running from VC to VC without much
hope of securing new capital, the
product development had come to a
grinding halt– the company was close
to shutting down.
XSOFT had started off as a really
promising company, yet it failed mis-
erably. What had gone wrong?
This story –as extreme as it sounds-
is often the reality for a lot of young
companies. In our daily work with
Athena CFO, we see many companies
with financials that aren’t managed
properly. Based on our experience,
companies with neglected financials
have a severe disadvantage in the
market, and often fail to achieve
sustainable success. With that being
the case, we would like to draw the
attention to five financial elements
of your company that can be easily
managed with a bit of attention, but
can endanger the venture if not man-
aged properly.
1. Financial planning
Financial planning means to build
a financial model that more or less
accurately predicts the future. This
model will give an estimate on rev-
enues, costs
of goods sold,
overhead and
cash flow.
Obviously, in a
young com-
pany the model
will not be
accurate and is
based on many
assumptions.
As the com-
pany develops,
more and more
of the assumptions become reality or
can be tested reliably.
A good financial model has a
separate section for assumptions,
uses lots of formulas linking to those
assumptions, goes not only deep (i.e.
covers a wide spectrum of revenue
and cost components), but also wide
(i.e. covers minimum a quarterly or
better monthly overview and runs up
to three years). In a good model, the
timing of funding requirements are
easily visible and worst and best case
scenarios flow through the model. A
very good model has assumptions that
accurately describe the key revenue
drivers and model along with expense
forecasts as the company grows.
Developing a financial plan is cum-
bersome. It eats up a lot of time of the
whole team, time that could be spent
talking to customers. But worse: a
financial plan of a young company is
never how the future really plays out.
The company will pivot and change
over many iterations; nonetheless,
capturing the key assumptions are
critical. A strong financial plan helps
in various ways:
• It supports the structuring of the
team’s thinking;
• It identifies the company’s revenue
drivers;
• It uncovers missing or overlooked
elements of the business;
• The process of drafting the plan
prompts the team to think about
spend, which again leads to financial
discipline.
Going back to the earlier example of
XSOFT, developing a financial plan
would have been crucial to ensure its
long-term success. With it, the start-
up team would have seen that cash
was limited months earlier, and could
have thus assigned resources towards
cost discipline and fundraising.
2. Financial infrastructure
Comparable to a city’s traffic in-
frastructure, a company’s financial
infrastructure is the backbone, the
core, of the company. It starts with
the streets (an ERP or financial book-
keeping system for smaller compa-
nies, inventory tools, sales force, HR
tools, etc.), over junctions linking
streets (the connections between and
into other systems or channels– like
the customer’s accounts payable >>>
Page 58
Entrepreneur february 2017
58
money ask the money guy | vc viewpoint | your money | ECON
Reports help to structure and to
identify a pattern. There is a good
chance that once you have set up a
regular reporting structure, it will
take you only very little time to go
through. You will know the drivers
of your business without spending
much time on the report.
With XSOFT, a CFO would have en-
sured a financial plan is in place,
they would have seen the cash flow
need well in advance, and they’d
have thus started the fundraising
process. A CFO would also have told
the CEO that they need to be vigilant
in the company’s spending behavior,
and they would have put controls
in place to maintain a record.
Heather Henyon,
co-founder,
Athena CFO
functions or the logistics team), and
the road rules (i.e. the policies, pro-
cesses, and governance structures)
to the traffic police (the controls and
the governance body).
Without traffic infrastructure, a
city would collapse when there is a
sudden increase in traffic or an ac-
cident blocking the road. The same
thing happened to XSOFT: for weeks,
there was no invoicing– customers
didn’t pay. It’s clear that they hadn’t
invoiced properly or followed up
on payments- a clear credit collec-
tion policy would have helped. After
all, no customer in the world pays
without having received a request to
do so. So, in terms of best practices,
companies need to ensure that:
• They have the right systems and
tools in place. In today’s world, there
are dozens of suitable apps and tools
online available for a minimal charge
for accounting, HR, expense claims,
CRM, inventory management, report-
ing, point of sale, document manage-
ment– you get the point. No company
should run their accounting on Excel,
or have tedious expense claim pro-
cesses, when they can easily set up a
professional system.
• The systems work. This is some-
what obvious, but often they don’t,
and specifically do not interlink
between the tools, which could help
avoid a huge amount of admin work
in bridging between them.
• They have a suitable level of
policies and procedures in place: too
much ties the company down and
kills creativity, too little results in
chaotic processes, intense coordina-
tion of team members who might not
be 100% familiar with their tasks
cost time and leads the attention of
the high management (such as the
CEO) on such small details instead of
important tasks in order to be able to
lead the company to success.
At our organization, Athena CFO,
we usually start with a small busi-
ness accounting system like Xero or
Quickbooks, and then integrate other
tools like an HR tool, a document
management tool or an expense claim
tool like Xpenditure or webexpenses.
Data can usually be integrated be-
tween the tools automatically. Yes,
setting up and running those tools
costs a bit of money; however, if at
the same time you can save on admin
tasks, there is usually a business case
to be made for it.
3. Budget
A budget is a plan for spending, but
also for income, usually broken down
by month for the upcoming year- and
yes, should be completed prior to the
start of the year! Personally, we don’t
like budgets. They are rigid, they
often limit a team’s creativity, and
they are a lot of work to set up and
maintain. But we still believe that as
soon as companies grow to a certain
size, budgets are essentially required.
There are two components to a good
budget: a well-drafted budget, and a
well-driven budgeting process.
A good budget finds the right bal-
ance between a forced down number
and a bottom up generated figure. It
further supports –similar to the fi-
nancial planning process– the struc-
turing of the team. It also helps the
team to stay within a certain limit
spending; it gives them something to
work within.
A well-driven budgeting process has
three elements: it allows flexibility
once the world around the company
changes, it is reasonably timed (i.e.
the budgeting process happens in
un-busy times and does not take too
long), and it also aligns the depart-
ments of the business to the same
company objectives.
For XSOFT, a budget would have
meant to allocate funds to, let’s
say, the development team and the
marketing team– within the avail-
able funds. For one of our customers,
a budget process meant to give the
teams a range to work within. They
did not know if they could hire the
expensive but super good consult-
ant, or if they should rather take
a cheaper but weaker recruit. As a
consequence, they discussed forever
on it, but never came to a decision.
Once we put a budget in place, they
were able to calculate the impact and
the remaining funds, and then moved
on to the next topic on their table.
Page 59
february 2017 Entrepreneur
59
Dr. Christiane Schloderer and Heather Henyon are the co-founders
of Athena CFO. Athena CFO supports investors and management of
growing companies strategically throughout the company’s life cycle
with their financial needs such as fundraising strategy and readiness
(debt or equity), capital and share structure (incl. ESOP), reporting
(investor or stakeholder), cash and profitability improvements, financial
restructuring and more. Athena CFO’s team also takes part-time finance
role responsibilities and operates a company’s finance function on an
outsourced basis.
With experience as a Corporate CFO, Finance Specialist and Turnaround
Expert, Dr. Christiane Schloderer has helped a joint venture in Saudi
Arabia grow from 500 to 1000 employees in two years, has financed
“unfinanceable businesses” and worked with a number of companies to
increase performance.
Heather Henyon is an investment guru, microfinance expert and angel
investor network founder. Heather has closed more than 20 microfinance
debt transactions, founded the first social business in the Arab region,
and launched the first women’s angel investor group in the Middle East.
The strategic finance person should
interact with the CEO and is part of
the management team. Often, the CFO
reports directly to the company’s
board of directors as a matter of good
governance. A CFO does not need to be
expensive though- they can be hired
part-time or on outsourced basis.
Dr. Christiane
Schloderer,
Founding Partner,
Athena CFO
4. Reporting
In our daily work with SMEs and
small corporates, we are constantly
surprised at the low level of reports
that are being prepared, discussed,
and shared with the team. Share-
holders need high level key perfor-
mance indicators (KPIs), manage-
ment need to be able to get involved
when necessary, and department
heads need to be able to drill down
into their own strategic reports.
Of course, no one wants a com-
pany that has a lot of the workforce
reporting most of the time. I have
worked with a company where the
finance manager could not go to
meet the customer and discuss the
outstanding payment because he had
to prepare the report. But I have also
worked with companies that had
no idea how much they spent two
months ago and did most of their
business decisions based on a very
short-term memory.
Reports help –again– to structure
and to identify a pattern. There is a
good chance that once you have set
up a regular reporting structure, it
will take you only very little time to
go through. You will know the drivers
of your business without spending
much time on the report.
5. Financial expertise
on the team
Many CEOs I met have a relatively
good understanding of financials,
some come with an MBA, others
however, say: I am not a finance
person; I don’t want to deal with the
numbers. Whatever financial exper-
tise the CEO has, there are usually
three levels of finance competence
any company needs:
Transactional tasks A book-
keeper, an accounts payable account-
ant or a business analyst- these
employees form the core of this par-
ticular function. They are often easy
to source in the market and not too
expensive. However, most of them do
not have experience in the higher-
level financial decision-making.
Financial management The ac-
countant, the controller, the senior
analyst: these are the people who
translate the numbers into business
language. They go to customer meet-
ings, engage with banks, and support
the business units in their decision-
making.
Strategic finance This is typically
done by the CFO or the finance direc-
tor. On this level, finance becomes
very valuable for an organization
because this person brings in specific
financial competences that have an
exponentially positive impact on the
organization. The strategic finance
person should also interact with the
CEO and is part of the management
team. Often, the CFO reports directly
to the company’s board of directors
as a matter of good governance. A
CFO does not need to be expensive
though- they can be hired part-time
or on outsourced basis; we, at Athena
CFO, have such part-time staff avail-
able.
An issue that can occur here is
when a small company tries to com-
bine all of the above three compe-
tence levels into a single role. The
problem is that a good bookkeeper is
usually not a good strategist, and a
good CFO often gets bored building
reports. We have worked with several
companies where the CEO ended
up taking the strategic finance role,
bridging between the accountant and
the management. While many CEOs
might have a very solid financial
understanding, taking on this role is
not what they should be doing: CEOs
need to be out there, developing
strategies, talking to customers and
guiding the team, not fundraising or
reporting.
With XSOFT, a CFO would have
ensured a financial plan is in place,
they would have seen the cash flow
need well in advance, and they’d have
thus started the fundraising process.
A CFO would also have told the CEO
that they need to be vigilant in the
company’s spending behavior, and
they would have put controls in place
to maintain a record.
In sum: entrepreneurs are busy. They
worry about product development
and customer acquisition. However,
even the most busy entrepreneur
eventually needs to have access to
enough funds to run and develop the
business– and funds come both from
fundraising, as well as from customer
payments, and is reduced by spend.
As with most things in life: funds
don’t just happen. Having enough
funds means to be properly prepared,
to have the right structure in the
business and the right people work-
ing on it– internally or externally.
This is where being financially well
managed can save a lot of hassle, time
and money down the line. And often
it is a key differentiator from your
competition- and thereby allows your
company to grow.
Page 60
Entrepreneur february 2017
60
money ask the money guy | vc viewpoint | your money | ECON
Four ways to better your business’s chances of a successful exit
By Ara Sahakian
Maximizing value
Ara Sahakian is an investor, advisor and a business owner. Previously a director at HSBC Private Equity ME, he is the founder of Incubate Advisory, a
boutique transaction advisory firm, helping private equity investors and business owners with acquisitions and exits. A CPA and CA with a Masters
degree in Accounting, Ara began his career with PwC Toronto and helped establish the transaction advisory practice in PwC Dubai. Ara has founded
several successful businesses and continues to seek investment opportunities. www.incubateadvisory.com
Sharing the reins may be your biggest
challenge ever. But it will be well worth
it as it may give you an additional exit
option- exiting without really exiting.
Y
ou have devoted countless
hours and made numer-
ous sacrifices to achieve the
dream of many: to build a
successful business. It’s now
time to reap the fruits of your labor,
and start enjoying your financial free-
dom. It’s time to plan your exit.
Selling your business can be one of
the most financially rewarding, yet
stressful events in your life. It can be a
grueling process, taking away precious
time from operating your business with
no certainty of financial close, as trans-
actions can fall through at any point in
time.
Many transactions are abandoned
during the due diligence process, when
large deal issues or a combination of
smaller issues are highlighted to inves-
tors by professional advisors. In many
cases, these deal issues could have been
avoided by owners.
Based on our experience with trans-
actions, the following are four simple
improvements you can make to your
business to increase its valuation, help
negotiate better terms and increase the
likelihood of a successful transactions.
1. Build a management team You
are key to your business, making the
most important decisions and even
driving sales. But do you have a succes-
sion plan in place? Although investors
are likely interested in your business
due to your leadership, you are prob-
ably the single largest risk to them.
The simplest way to mitigate this
risk is to plan for your own succession
and build and empower a manage-
ment team. This may require a cul-
tural change and will definitely require
strong operating and reporting systems,
regular management meetings and
significant investment in developing
your people.
Sharing the reins may be your biggest
challenge ever. But it will be well worth
it as it may give you an additional exit
option- exiting without really exiting.
If your business is being successfully
managed by a team, you may not have
to sell your business. Instead, you could
move to a board position, reduce your
day-to-day involvement and enjoy
whatever it is you prefer to be doing.
2. Build a strong finance team
When was the last time your finance
team questioned one of your decisions?
One of the most common deal issues
that can be avoided is a weak finance
team.
Investors need to rely on financial
information to make their investment
decision and need a strong finance team
to help them manage the business post
acquisition. Without accurate financial
information, informed decisions cannot
be made.
A strong finance function requires a
strong leader that can challenge and
add value to your decisions, has mod-
ern financial reporting systems in place,
produces accurate and timely monthly
reports, tracks budgets and forecasts
and produces annual audited financial
statements.
A strong finance team can work well
with a management team, helping you
exit without really exiting.
3. Legal structure One of the most
common avoidable deal breakers is not
having the proper license in place re-
flecting the activities of your business.
Investors will simply avoid acquiring
a business that may breach local laws,
therefore, getting the right license is
imperative.
If you have multiple licenses or busi-
nesses, it may also be useful to have
a legal holding company structure to
facilitate the transfer of your shares to
the new shareholder. An offshore hold-
ing company structure may be useful
for holding local company shares, al-
lowing more tailored shareholder agree-
ments with different classes of shares
under English law.
Page 61
february 2017 Entrepreneur
61
I
n today’s complex economic environment,
entrepreneurship and innovation have
been key in establishing a new status quo
that shies away from the Pareto efficiency
model. As the famous economist Joseph Alois
Schumpeter said: “Carrying out innovations
is the only function which is fundamental in
history.” Had he been alive today, Schumpeter
would’ve witnessed his “entrepreneurship
theories” come to life, as the landscape of to-
day’s economy accommodates more startups
and entrepreneurs and more VCs.
In the US alone, the number of on-campus
entrepreneurship programs offered in uni-
versities has increased from 180 to 2000+
between 1990 and 2014. 27 million Americans
are starting or running new businesses. It
comes as no surprise that the US itself tops
the Global Entrepreneurship Index (GEI) due
to its attractive ecosystem, resources and
infrastructure. On a global scale, top perform-
ing countries present in the same list include
Switzerland, Canada, Sweden, Denmark,
Australia, UK & Ireland, Netherlands. The
United Arab Emirates ranks 19th with an index
of 58.8.
Another major entrepreneurship indicator is
VC activity. Indeed, in the past two years, the
total value of VC activity has been stead-
ily growing from US$55 billion in 2013 to
US$148 billion in 2015, experiencing almost
a three-fold increase. The US dominated in
terms of numbers of deals and total value:
3916 deals and US$72.3 billion. It is interest-
ing to note however that two out of three of
the most important deals were China-based.
The VC activity in China in 2015 totaled
US$49.2 billion with 1611 deals, an impressive
number when compared to European activity,
the latter completing 1598 deals of a total
value of US$14.4 billion.
While the “unicorn club” is looking bleaker
for recent entrepreneurs to join, continuous
“innovative activities” are considered as a sign
of a healthy economy and economic well-
being, since it inherently develops a country’s
general output and increases the “knowledge
stock.” However, at the rate at which tech-
nology is changing, we now talk about the
rise of “intrapreneurs”. They are people with
entrepreneurial spirit within companies that
take the necessary risks in an effort to keep
innovating, and getting ahead of the curve.
Check out the infographic to get a sense of
more of the trends being seen in entrepre-
neurship around the globe.
By The Infographic.ly Team
This article by Ara is based off a
talk he gave to the British Business
Group Dubai & Northern Emirates at
a breakfast session on the subject
of exit strategies, focusing on how
to add value to your business prior
to exit or raising capital. The British
Business Group Dubai and Northern
Emirates (BBG) is the region’s
foremost business-to-business
membership networking group,
enabling like-minded professionals to
further their business interests in the
UAE and wider region.
www.bbgdubai.org
Infographic.ly is a UAE-based information design agency that uses your data to design compelling visuals your
audience can understand. Core services include infographics, motion graphic videos, data visualizations, reports
and presentation design. MasterCard, Mercedes Benz, TED Institute, WIRED UK, Reebok, BMW Foundation, and
Dubai Prime Minister’s Office are some of the notable brands & companies Infographic.ly has designed for.
Trend watch
Charting the growth of entrepreneurship around the globe
Other avoidable deal issues
include not having a brand
properly registered, operat-
ing under a different brand
than the registered trade
license and employees not
registered under the trade
license.
4. Sell side due dili-
gence One service that
can help you prepare for an
exit is a sell side or vendor
due diligence, whereby
a professional advisory
firm, such as my company,
Incubate Advisory, is hired
to perform a due diligence
on the business on behalf
of the business owner. This
is a proactive approach
whereby risks are identi-
fied and addressed early
in the process, before they
become deal breakers. It also
helps prepare for potential
negotiating points and may
even highlight matters that
may potentially increase the
value of your business. A
sell side due diligence may
also give potential buyers
comfort before investing,
augment internal resources
for a potential transaction
and put the business owner
in control of the process, ac-
celerating the time to close.
Selling your business can
be a time consuming pro-
cess. The key to adding value
to your business before you
exit is being prepared. You
may want to consider hiring
professional advisers to help
you manage the process, and
to help you maximize the
value to your business.
Page 62
Entrepreneur february 2017
62
money ask the money guy | vc viewpoint | your money | ECON
Why the UAE’s new venture capital regulations
will help the ecosystem
By Jon Richards
Moving ahead
Jon Richards is the co-founder and CEO of the Middle East’s leading finance comparison site, compareit4me.com. With 10 years of digital marketing
experience in the UK and the UAE, Jon first immersed himself in the Middle East’s digital startup ecosystem with propertyfinder.ae. Jon founded
compareit4me.com in August 2011 and moved into a full-time role as CEO of the company in 2014. His passion for innovative technology and
industry disruption has led to him continually pushing to expand the compareit4me.com brand and its offering. The company has so far raised
almost US$6 million from some of the region’s leading VCs, employs around 65 people, operates across nine countries. compareit4me.com also
recently launched the UAE’s first fully transactional car insurance comparison portal.
A
t the beginning of the year,
the UAE government an-
nounced new regulations
for venture capital funds
operating in the country. And
while the actual wording of the new
regulations hasn’t been released –even
lawyer friends of mine haven’t been able
to get their hands on the document–
the announcement contains plenty for
entrepreneurs and venture capitalists to
sink their teeth in to.
What will the new regulations mean
for the local ecosystem? Well, we’ll get
into the finer details of the announce-
ment in a minute, but let’s start by
providing an overview. Essentially, the
regulations result in more checks and
balances being imposed on venture
capital firms operating in the UAE. So
are the new regulations a bane, creating
extra paperwork when what we need is
more dynamism? Or are they a boon,
bringing the UAE venture capital scene
up to international standards?
I’ll say from the outset that I believe
the regulations are a positive develop-
ment, and should achieve their stated
aim of attracting venture capital funds
to the country. And I’m not alone in
that belief– plenty of investors, lawyers
and entrepreneurs I’ve spoken to share
the same optimism about the new legal
system.
So what does the system entail? Well,
for starters, it imposes reporting obliga-
tions on venture capital firms. If the
value of the assets under your manage-
ment exceeds AED180 million, you’ll
have to issue an annual report according
to IFRS standards, appoint a risk man-
agement officer, and ensure that your
risk exposure is equal to or less than the
fund’s net asset value. And if the value
of the assets under your man-
agement is less than AED180
million, you won’t have to
worry about a lot of that stuff,
but you’ll still need to draft an
annual financial report, as well
as stick to the rule regarding
risk exposure.
So, if you’re a really large
firm, you’ll have to conduct
proper, world-standard fi-
nancial reporting, and even if
you’re not that large, you’ll still have to
manage your risk exposure. That’s a key
point to take away– the UAE government
is encouraging venture capital firms to
be responsible with their investments
with these regulations.
Now, you could argue that this might
create a climate in which venture capital
firms become more risk-averse, thereby
impacting investment for startups
that need funding. But, to me, that
shouldn’t be a worry. Venture capital
firms, by their very nature, assume a
certain amount of risk when they invest
in startups. Bringing their accounting
practices up to international standards
won’t change their hunger for buying
into exciting new businesses.
As the owner of startup, then, getting
investment will simply require that your
business plan be backed up by solid
financials. If you have enough startups
doing that, before you know it, the good-
practice bar for accounting will have
been raised across the ecosystem.
This is crucial if we’re to attract in-
ternational venture capital firms to the
region. Not to take anything away from
the ones already operating here, but we
want more. More investors means more
competition, and that means better
valuations and a more diverse ecosys-
tem. At Series B, for example, where
serious money is needed, there are only
a very small number of players that can
actually take part in the rounds. Attract-
ing international investors should help
to plug that gap.
The new regulations also deal with
how funds should be allocated. The
headline here is that at least 70% of a
venture capital firm’s assets should be
invested in one of more of a few do-
mains. That includes new or troubled
Page 63
february 2017 Entrepreneur
63
Over 30 sessions, insights of 80
speakers, more than 15 hours of
workshops, four challenges, and
much more await participants at
ArabNet Beirut 2017, set to be held
on February 20-22, 2017 at Hilton
Habtoor Grand Hotel in Beirut. In
its eighth edition, the key regional
gathering of digital businesses
estimates over 1,300 corporate
executives, entrepreneurs and
investors to come together to discuss
the latest trends in the region’s
tech sector. ArabNet believes that
with the venture capital climate in
Lebanon being robust than ever, the
conference could be a perfect venue
for the tech and entrepreneurial
communities to explore partnerships.
The key components of the three-
day conference include The Banking
Innovation Day, a session that will
bring together bankers and tech
companies to discuss innovations
in the areas of digital marketing
and digital products, sessions
around the state of innovation and
entrepreneurship in the region, and
discussions on latest technologies
that can be leveraged by the
advertising, media and marketing
world.
Besides keynotes and workshops
planned for the three days, ArabNet
Beirut also plays host to ArabNet’s
flagship Techfair exhibition that
will feature over 50 tech regional
and international companies and
their products. For the entrepreneur
community, the event organizes the
Startup Battle competition- a pitch
competition for growing companies,
and The Ideathon competition for
aspiring entrepreneurs to showcase
their business ideas to entrepreneurs
and investors. Also on the agenda
this year are creative challenges such
as the Creative Combat, which hunts
for young talents in the regional
advertising and media industries,
and Innovation Avenue, a challenge
offering hardware developers and
designers in the MENA region to
showcase their products. Speakers
who will be a part of the event include
Elizabeth Lumley, MD, London
Startup Bootcamp Fintech, Olivier
Cohen, Regional Manager – Middle
East, Hootsuite, Erik Katz, founder
and CEO, Circuit Launch, and others.
Beirut Digital District, OMD, LBC
International and others are a few
partners for the conference.
Get ready for ArabNet Beirut 2017
Time to talk digital
if you’re a really large firm, you’ll
have to conduct proper, world-
standard financial reporting,
and even if you’re not that large,
you’ll still have to manage your
risk exposure. That’s a key point to
take away– the UAE government is
encouraging venture capital firms
to be responsible with their in-
vestments with these regulations.
A panel
discussion at
ArabNet Beirut
2016
A scene from ArabNet Beirut 2016
IMAGEs courtesy arabnet
projects (though they’ll only be able to
invest 30% of their assets into these
sorts of businesses), and equity instru-
ments issued by unlisted companies
(read: most SMEs looking for funding).
Venture capital firms can also choose to
invest in units of other venture capital
firms, though only up to 10% of their
total assets.
There’s quite a lot to unpack there, but
the long and short of it is that the regu-
lations are encouraging venture capital
firms to not only ensure that their funds
are actually being used to invest in UAE
businesses, but also that the funds are
distributed fairly across a range of busi-
ness types.
We don’t yet know how the new regu-
lations will play out, but as they’re im-
posed on the market, I reckon that we’ll
begin to see a more dynamic investment
landscape that encourages and rewards
innovative startups with solid financials.
This doesn’t mean that you’ll have to be
raking in serious cash in order to receive
investment; it simply means that, if you
can demonstrate an ability to turn a
profit with your business plan, you’ll be
more attractive to investors. That much
should be obvious to any business owner
anyway, but that obligation is now being
written into the legal framework.
I look at these new regulations with
a sense of optimism– anything that
encourages venture capital firms coming
to the Middle East and investing more
money has to be a positive thing. The
ecosystem needs to continue to grow.
We’ve seen some great results with the
likes of Souq.com, Careem and Proper-
tyfinder raising serious money. And as
some of these guys start to exit –wheth-
er that’s listing or actually M&A activity,
or whether they exit to bigger, interna-
tional players– there’ll be even more of
a reason for international firms to invest
in this region. And that’ll pave the way
for newer startups to get funding.
Page 64
Entrepreneur february 2017
64
UAE digital execs come together for IBM-powered
“Digital Leaders” session
Digital discussions
in pictures
The gathering for the first Digital
Leaders session in Dubai
Emirates NBD’s Pedro Carduso
and du’s Stacy Holland
IBM’s J.J. De La Torre with guests at
the Digital Leaders session
The Digital Leaders gathering at
Alserkal Avenue in Dubai
IMAGE CREDITS: ibm
S
ome of the UAE’s most
prominent figures in
the country’s digital
space came together
in January in Dubai’s Alserkal
Avenue for a close-knit
gathering powered by IBM,
which saw these profes-
sionals discuss the digital
challenges they face across
industries, and how they
can help support and move
forward a digital agenda in
the Emirates. Led by J. J. De
La Torre, Digital Transforma-
tion Leader for the Middle
East and Africa at IBM, the
invite-only breakfast session
for the UAE’s “Digital Lead-
ers” saw representatives from
sectors like telecom, banking,
media, etc. come together
and engage in conversations
on furthering digital adop-
tion in the country. The event
had attendees from both the
corporate and startup spaces-
these included Stacy Hol-
land, Vice President – Digital
Experience, du, Pedro S.
Cardoso, Head of Multichan-
nel and CRM, Emirates NBD,
Wissam Younane, CEO, BNC
Publishing, Philip Bahoshy,
founder, MAGNiTT and Aby
Sam Thomas, Editor in Chief,
Entrepreneur Middle East,
among others. Commenting
on the gathering, Bahoshy
said, “MAGNiTT looks to
bring together startups and
stakeholders from across
the ecosystem. Connectivity
and discussion is key to that
proposition. As its founder,
I believe more collaboration
and cooperation is needed
across the MENA region to
help support startups. Efforts
like this are great in creating
those links and connections,
which previously wouldn’t
have taken place.” As the
organizer of the event, De La
Torre said he was very happy
with the turnout for the inau-
gural Digital Leaders session,
and was looking forward to
more editions of the same in
the future. “We are pleased
to have enabled this Digital
Leaders gathering,” De La
Torre said. “This is the first
time something like this has
been done in the Emirates,
and we are keen on sup-
porting the country’s digital
agenda.”
Page 65
Page 66
Entrepreneur february 2017
66
Rajesh Sajnani is the CEO of the RVS group of companies, a
fully integrated fashion group in the Middle East that caters
to all the steps of fashion development, right from textile
creation to fashion designing to wholesaling and retailing of
high end fashion wear and franchising. He likes innovations and
experimentations, and likes to push technique to the limit.
Paul Kenny is one of the leading technology founders in the
Middle East. Having founded his first venture at the age of
25, Paul went on to start four companies before the age of
30. At the age of 28, Paul exited his first venture, and he is
now a Partner at Emerge Ventures, which is investing into
early-stage growth companies in the Middle East.
The generation gap
[in entrepreneurs]
Comparing old school practices with new millennial outlooks on starting
your own business By Paul Kenny and Rajesh Sajnani
ecosystem | who’s got VC | Q&A | STARTUP FINANCE
start it up
Technological integration
is often seen as one of the
largest distinguishing fac-
tors between generations
of startups. Older genera-
tions tend not to be as tech
savvy, but all businesspeople
are capable of seeing the
benefits in embracing what
technology has to offer.
G
enerational change is
a media and marketing
phenomenon- news-
papers have sepa-
rate sections geared
to retired baby boomers,
magazine covers show off
new leaders from Generation
X, and now, millennials. En-
trepreneurs launching their
businesses over the past few
decades have been granted
the advantage of watching
the successes and failures of
their predecessors. From the
“veterans of change” born
from 1925-45, to the baby
boomers born from 1946-64,
there is a lot to learn, but the
social, economic and political
landscapes across the globe
have grown just as quickly as
Generation X and millennial
babies.
A generation has a shared
memory of important events
and similar assumptions
about what matters, based on
their formative experiences.
Of course, there are natural
subgroups, such as due to
religion, class, and ethnicity,
but there are also common
markers. Baby boomers, for
instance, tend to assume
they have the power to make
change. Even with a strong
belief in hierarchy, they try
to be more inclusive in the
workplace, but this genera-
tion is rapidly exiting the
workforce, if they haven’t
exited already. Generation X-
ers and millennials have been
and continue to be poised
to step into their roles and
launch their own entrepre-
neurial ventures. The busi-
ness tactics, characteristics
and leadership styles of these
two groups have been a hot
topic of discussion. With the
self-reliant Gen X working
with their peers, results are
always the most important
aspect of their work, whereas
millennials showcase another
level of self-confidence. They
believe they will make a
difference through their
practical know-how. In this
globalized, connected and yet
polarized world that charac-
terizes the second decade of
the new millennium, employ-
ees are looking to leaders who
can make a difference now.
One thing that hasn’t
changed in entrepreneurs
across generations is passion.
In today’s world of business,
along with your passion, you
must also want to learn and
expand your skillset. Money
should not be the driving
force. Instead you should be
passionate about creating
something, doing the best
work that you can and solv-
ing people’s problems with
unique solutions. In a similar
vein, it’s clear that there is no
wrong or right time to start
a business. The right time is
when a business succeeds;
the wrong time, when it
fails. When launching a new
venture, there is an inevitable
air of uncertainty. Today’s
environment offers certain
challenges so an entrepreneur
always needs the ability to
adapt. Liquidity has all but
dried up, there is pressure
on demand, consumers are
looking for more value, and
with that, lies opportunity.
In every circumstance, there
are opportunities to build
amazing businesses. Where
we have seen tremendous
change, however, is the UAE’s
startup landscape, which
was practically non-existent
Page 67
february 2017 Entrepreneur
67
W
hile it’s always interesting to understand what
product sells and who is buying it in the e-com-
merce world, Dubai-based e-retailer JadoPado
decided to go the other way and tried to get to know the
region’s e-commerce sellers better through a survey it
conducted in December last year. In an infographic captur-
ing the findings of the survey, JadoPado says that it’s
clear that the online medium enables the growth of SMEs,
with 56% of sellers found to be small businesses with less
than five employees. Further, a desire to attract larger and
new pool of buyers has emerged as the dominant reason
for companies seeking to sell on the web, and 64% of the
sellers have even gone on to sell through multiple (more
than three) sales channels. While electronics, fashion, and
beauty products lead among the product categories sold
online, the majority of sellers note that commercially, e-
commerce delivers higher profit margins to the business.
The majority of online sellers also seem to concur on their
future business strategies, with 60% of survey respond-
ents picking “competitive pricing” as a key tool to stay
ahead of competition in 2017. Check out the infographic
below for a look at why and how the region’s sellers sell
online, alongside insights on their preferences.
stuffwelove.jadopado.com
Boosting business
JadoPado’s Middle East e-commerce seller survey
makes the case for SMEs to go online
| the fix |
social media plays a huge
role in today’s successful
businesses (even if they are
not social media businesses.)
Some now argue that if your
business isn’t on social
media, it doesn’t exist.
in the eighties and nineties.
There is a lot more op-
portunity now, with angel
investment available, social
media aiding your business
plans, and multiple financing
options easily available. The
UAE is a young, incredibly
dynamic and fast-growing
nation. Years ago, there was
not a talent pool to hire from,
or nearly as many support
services to support building
a company. Fast forward to
today, there are hundreds of
startups and so much talent.
Within such a short space of
time, this market has become
an amazing place to start
your company.
Technological integration
is often seen as one of the
largest distinguishing fac-
tors between generations of
startups. Older generations
tend not to be as tech savvy,
but all businesspeople are
capable of seeing the benefits
in embracing what technol-
ogy has to offer. Social media
plays a huge role in today’s
successful businesses (even
if they are not social media
businesses.) Some now argue
that if your business isn’t
on social media, it doesn’t
exist. Of course, technology
has been a core element of
younger entrepreneurs’ ca-
reers. Some businesses, such
as e-commerce companies,
couldn’t exist without it. For
B2C businesses, engaging
customers in conversation
improves trust and ulti-
mately can drive sales. Today,
businesses are more seam-
less, with the use of various
technologies that allow our
teams to work remotely,
driving cost efficiencies. It is
also a big challenge now for
non e-commerce businesses,
as it limits your method of
sales to footfall. Businesses
that began a few decades ago
only had to cater to their
local market, whereas now,
thanks to technology, the
world is your market. A few
years ago, it was more simple
and much more cost-effective
to start your own business
in the UAE with a lot less
regulation, whereas today’s
entrepreneurs will be reading
through the rules of DEWA,
Civil Defence, licensing
regulations, and the list goes
on. With the introduction
of Facebook algorithms and
click-through link monitor-
ing, marketing has changed
from an art to a science.
Additionally, the shelf life of
tech goods and services has
decreased significantly due
to regular innovation in our
technology, with businesses
becoming extinct if they fail
to change with the times.
Today’s customer is more
aware and therefore more
demanding, due to the ease
and availability of informa-
tion through the internet.
The hardest part of start-
ing your business is actually
starting. Many people have
great ideas, but they tend
to never follow those ideas
through any further than a
conversation. Difficulty is of-
ten found when turning that
idea into something tangible.
Ultimately, the ability to
continuously learn and never
give up is invaluable, regard-
less of your generation. What
works in one business doesn’t
work in another, so persever-
ance is paramount. A great
business isn’t built overnight,
but regardless of whether
you started 30 years ago, or
you’re starting tomorrow,
know that you’ll be putting
all of your energy and focus
into this over a long period
of time. And then, hopefully,
you’ll get to reap the large
rewards that entrepreneur-
ship can offer.
Page 68
Entrepreneur february 2017
68
Unlocking local pride
Three steps to building a sustainable entrepreneurial economy in the UAE
By Ramesh Jagannathan
ecosystem | who’s got VC | Q&A | STARTUP FINANCE
start it up
NYU
Abu Dhabi
campus
The UAE has a long tradition of
traders and business institu-
tions that can and should look
to invest in the future of their
country. Local investors have
to embrace the long-term view
of investing locally and in high
technology ventures, rather
than putting their money in
lucrative alternatives such as
real estate.
IMAGE CREDITS: NYUAD
At a time when Gulf econo-
mies have been affected by
declining oil prices, global
and historic precedents
illustrate the significance
of entrepreneurship for
economic development and
diversification. The West has
turned to an entrepreneurial
economy from a managed
economy, the BRICs (Brazil,
Russia, India and China) have
demonstrated their eco-
nomic versatility by utilizing
entrepreneurship as a means
to promote business opportu-
nities, and across developing
countries, youth entrepre-
neurship is being promoted
as the answer to the supply-
demand challenge of employ-
ment with decent wages.
The UAE has a young econ-
omy defined by a developing
entrepreneurship ecosystem.
The task ahead is to build
local capacity and business
from the ground up. This is
essential for successful and
sustainable diversification
of the economy. This is also
antithetical to the previous
rentier model the Emirates
relied on to drive growth,
a strategy that has been
well suited to an oil-driven
economy. In order to engineer
the transformation of the
oil-driven economy toward a
knowledge-based and entre-
preneurial economic model,
three core components
must be considered: getting
corporates involved, investor
participation, and community
education.
1. Getting corporates
involved Traditional ven-
ture capital is no longer the
only way to raise money for
startups. As many as 68%
of the top 100 companies
from the Forbes Global 500
are engaging with startups,
with the majority (61.7%)
of the startup companies
mentioned by The Wall Street
Journal under The Billion
Dollar Startups Club having
raised significant funding
from at least one corporate
entity, not including invest-
ment firms and banks.
It is not only leading com-
panies such as General Elec-
tric (GE), Oracle, and Google
who have taken a proactive
interest in startups; some
of the traditional corporate
players have explicit meth-
ods through which they may
invest in startups on a large
scale. Let’s take for example
the emerging industries in
the region: energy, aviation,
logistics, finance and health.
The UAE has a rich pipeline
of influential corporate lead-
ers who own these competen-
cies. They have unique access
to market knowledge, a huge
consumer base and domain
understanding. However,
the immense size of many
of these businesses limits
them from innovation. They
are battleships that cannot
change course on a dime.
This is in direct contrast with
the more agile and innova-
tive tech startups, which can
pivot and adapt at lightning
speed; however, they cannot
grow without domain exper-
tise and insights or access to
a large consumer base to test
viability.
The startAD incubator at
NYU Abu Dhabi has been
built to create a platform for
mutually beneficial exchange
between such corporates and
startups, allowing corpora-
tions to innovate effectively
through startups, and en-
couraging startups to validate
their business concepts
through corporations.
By connecting entrepreneurs
with leading UAE industry
players, we offer the chance
to engage with a network of
mentors as well as opportu-
nities for thorough business
viability testing. UAE corpo-
rates will benefit in the long
term, as startups help them
address new business chal-
lenges and also contribute to
an increasingly diverse entre-
preneurial economy through
job creation and technology
development.
2. Investor participa-
tion Local investors who
invest outside the UAE and
MENA region must take
encouragement from the
resurgent deal flow in the
region. The emergence of
startups in the UAE alone has
exploded over the past several
years as evidenced in the lat-
est reports from ArabNet and
MAGNiTT. A stronger local
investor community start-
ing from seed stage through
Page 69
february 2017 Entrepreneur
69
Ramesh Jagannathan is currently the Vice Provost for
Entrepreneurship Development and Managing Director of
startAD, the innovation and entrepreneurship platform at
NYU Abu Dhabi. Ramesh is an entrepreneurial technologist
specializing in leading global teams, converting abstract
concepts into tangible and marketable technologies in a short time frame. Since
2010, Ramesh has led the focus on innovation and entrepreneurship at NYU
Abu Dhabi.
Prior to startAD, Ramesh piloted an entrepreneurship program -IDEA Lab-
which connected NYUAD members with the broader startup community. He
also developed the “superlab” course for engineering students that sought
to introduce design concepts around abstract challenges. Previously, Ramesh
spent 30 years at Eastman Kodak in the US and the UK, which culminated in
a prestigious appointment as Research Fellow at Kodak Research Labs. A
recipient of the Kodak Distinguished Inventor Award and a distinguished
researcher, Ramesh sat on the Cambridge University Mentor Panel and the
Kodak Research Scientific Council.
Ramesh is a gold medalist from the University of Madras from where he
received his B.Tech degree. He went on to complete his Ph.D. from Clarkson
University. Ramesh holds 43 US patents, and has invented a dry inkjet
printing technology and a new atmospheric process for coating organic
device quality thin films. He also has 31 peer-reviewed articles in journals
such as the Nature Scientific Reports and Advanced Functional Materials,
including “Organic Nanoparticles — Preparation, Self-Assembly, and
Novel Properties,” one of the most accessed papers of 2006 in Advanced
Functional Materials.
the emergence of startups in
the UAE alone has exploded
over the past several years
as evidenced in the latest
reports from ArabNet and
MAGNiTT. A stronger local
investor community starting
from seed stage through to
Series, A, B and beyond is cru-
cial to building UAE’s entre-
preneurial economy.
NYU
Abu Dhabi
campus
to Series, A, B and beyond
is crucial to building UAE’s
entrepreneurial economy.
The time has come for lo-
cal investors to look locally
before investing their money
in Silicon Valley or offering
to fund European startups.
Local businesses are, after all,
what will form the basis of
a sustainable and successful
economy. Not only will local
businesses provide profitable
returns, they will also keep
the investors’ money circulat-
ing where they can see the
benefit it is bringing about.
It is no secret that the UAE
is home to a concentration of
high net worth individuals.
The UAE also has a long tradi-
tion of traders and business
institutions that can and
should look to invest in the
future of their country. Local
investors have to embrace the
long-term view of investing
locally and in high technology
ventures, rather than putting
their money in lucrative al-
ternatives such as real estate
and other tangibles elsewhere
in the world.
3. Community education
This process appears simple
on its face, but harder to
execute in reality. Innovators
in the UAE began by think-
ing they could borrow the
concept of accelerators and
incubators from the West
and apply the same formula
here with the same success.
However, this practice be-
comes far more complex when
dealing with an emerging
ecosystem.
The formula from the West
is not a replicable, out-of-the-
box solution in an emerging
ecosystem. The truth is that
what works in New York City
or London will not necessarily
work for Abu Dhabi. To en-
able the organic growth of the
entrepreneurial economy in
the UAE, a holistic approach
needs to be adopted: one that
works on building capacity in
the region.
Over the past few decades,
entrepreneurs and venture
capitalists have distilled
learnings that significantly
improved the prospects of
success for aspiring entre-
preneurs. Internalizing the
science and process of entre-
preneurship has resulted in
a recipe to create replicable,
scalable and capital efficient
ventures.
This process can be taught
by bringing together lead-
ers, researchers, founders,
and technology practitioners
to engage with the aspiring
entrepreneurs in the region.
By educating people in digital
and business literacy we want
to enable the local commu-
nity to not only set up their
own ventures, but to be more
effective in executing any pro-
ject throughout their careers.
With this, our hope is that
the general population will
become better informed, and
their resulting experiences
will instruct businesses on
how to get things right in or-
der to engineer the economy
of the future.
It is the pioneers in the
local community that will
lead the way in a “bottom
up” approach. As much as
government leaders can
infuse capital into this space,
the transformation will not
be truly effected without
the community of existing
and aspiring entrepreneurs
taking ownership. It is their
innovative projects that will
grow the economy; and these
ventures will help build the
infrastructure for new busi-
nesses to expand through, and
further the UAE economy.
Page 70
Page 71
Page 72
Entrepreneur february 2017
72
Calling fintech entrepreneurs
Dubai International Financial Centre and Accenture
launch FinTech Hive in the UAE
By Sindhu Hariharan
ecosystem | who’s got VC | Q&A | STARTUP FINANCE
start it up
“The program targets
startup companies that
have already reached a
certain stage of maturity
in their business, and
are looking for minor
financial investment,
as well as access to a
network of field experts”
Amr El Saadani,
MD- Financial
Services MENA,
Accenture
H.E. Essa Kazim,
Governor of DIFC, at
the launch of FinTech
Hive in DIFC
Global consulting firm
Accenture has joined hands
with Dubai International
Financial Centre (DIFC)
to launch FinTech Hive, a
regional fintech accelerator
program set to commence
in the first quarter of 2017.
FinTech Hive aims to create
a platform that can bring to-
gether financial institutions
and new age financial tech-
nology companies, with an
objective to “increase access
to, improve customer experi-
ence and drive operational
efficiencies” in the financial
services industry. Explaining
its two-fold benefits, Pinaki
Aich, Vice President-Group
Strategy, DIFC, says that the
accelerator will serve as a
launch pad for “relevant and
cutting-edge technology”
pertaining to the financial
market, and will enable re-
gional conventional entities
to tap into tech innovations.
The accelerator will identify
entrepreneurs and startups
through a competitive evalu-
ation process, and help them
“develop, test and modify”
their businesses by offering
financial investment and
access to network of men-
tors. “The accelerator will
invite applications from
global firms planning to ac-
cess the Middle East, Africa
and South Asia (MEASA)
markets, and will take
entrants through a series of
mentorship and co-working
sessions for a period of 12
weeks,” Aich says. “This will
culminate with a demo day
where startups will dis-
play their work and engage
with tech firms as potential
customers and investors.”
While FinTech Hive plans
to select 8-10 startups per
cycle, this number will vary
depending on the number
of applications, which are
expected to open by March
2017. “We will also continue
to expand these partnerships
and engage this industry in
new ways,” says Aich. Urging
fintech entrepreneurs to
apply for the program, Aich
stresses that the local en-
trepreneurship community
will “without doubt benefit
immensely from exposure to
global technological know-
how and talent.”
With respect to the partner-
ship with Accenture, both
parties expect the accelera-
tor to gain from the consult-
ing firm’s global experience
and expertise in building and
running three FinTech Inno-
vation Labs in London, New
York and Hong Kong. Com-
menting on the FinTech Hive
initiative, Amr El Saadani,
MD, Accenture’s Financial
Services Practice in MENA,
says that the company’s
responsibilities will involve
staffing, budgeting, and man-
agement. “Additionally, we
will be putting together the
list of activities and events
we can host at the accelera-
tor,” he says. “The program
targets startup companies
that have already reached
a certain stage of maturity
in their business, and are
looking for minor financial
investment, as well as access
to a network of field ex-
perts,” he adds. DIFC, on its
part, believes that the col-
laboration will help in com-
mercialization of technolo-
gies relating to “blockchain
empowered trade finance,
stock exchange, payments,”
among others. “One of the
main benefits is shortening
and easing of go-to-market
strategy for involved firms,
with the opportunity to
develop relationships with
potential future institutional
clients and develop relation-
ships with senior execu-
tives,” says Aich.
Globally, even as fintech’s
attraction as a sector is
increasing, the MENA region
has lagged behind its in-
ternational counterparts in
developing workable models,
Page 73
february 2017 Entrepreneur
73
THE EXECUTIVE SUMMARY
Pinaki Aich, Vice President-
Group Strategy, DIFC
What selection methodology will
be used to pick entrepreneurs
forming part of the accelerator
program?
“FinTech Hive at DIFC intends to draw
a pathway for examples of successful
fintech innovation deployment in the
regional financial services industry,
as well as set new benchmarks for
attracting venture capital from the
regional markets as the industry
grows. Overall, given the fact that one
of FinTech Hive’s main objectives is to
shorten and ease the go-to-market
strategy for tech firms to the MEASA
region,
startups that
are likely to
be successful
in becoming
a part of the
program will
require a cer-
tain profile in
terms of their
maturity, life
stage, market traction and financing.
The evaluation mentorship commit-
tee we have selected, that consists of
representatives from DIFC, Accenture
and each of our partnered Financial
Institutions, will ensure the right mix
from across the financial services
landscape, who will collectively define
the common problems faced by the
industry.”
What are your views on the recent
fintech policy/regulations brought
out by UAE’s Central bank?
“We welcome the regulations brought
out by UAE’s Central Bank. It is
important that for all modern banking
practices, regulations are frequently
updated. This encourages innovation
and flexibility for a large, 70% un-
banked market in the MEASA region
that has access to online tools and a
smartphone usage of up to 80% while
still protecting the consumer. Innova-
tion in this market is never in isolation
and the more participants that come
forward in a collaborative sense, the
better it will be for the region and the
growth of the fintech sector.”
“One of the main benefits is shortening
and easing of go-to-market strategy for
involved firms, with the opportunity to
develop relationships with potential
future institutional clients and develop
relationships with senior executives.”
Pinaki
Aich
DIFC Authority CEO Arif Amiri with Omar Boulos, Regional MD of Accenture in the MENA
at the launch of FinTech Hive
Launch of
FinTech Hive
at DIFC
and in joining this fintech revolution.
As per a 2015 report on fintech eco-
system in the GCC by Strategy&, this
could soon change because the four key
elements necessary to nurture a sup-
portive ecosystem, namely “the busi-
ness environment/access to markets,
government/regulatory support, access
to capital, and financial expertise,” are
gradually emerging in the region. While
the DIFC-Accenture partnership is one
instance of this change, the region’s
entrepreneurs have been blessed with
a plethora of support systems when it
comes to starting fintech businesses.
2016 has witnessed some fierce com-
petition, among the region’s nations
as well as corporations, in this regard.
Some of these initia-
tives include a part-
nership between The
Financial Services
Regulatory Authority
(FSRA) of the Abu
Dhabi Global Market
(ADGM) and Flat-
6Labs to grow Abu
Dhabi’s fintech eco-
system, the proposal
to set up ADGM’s
proposed Fintech
Regulatory Labora-
tory- a incubator to
innovate in the financial industry in a
regulated environment, fintech startup
PayFort’s regional accelerator Fintech
Factory, and Flat6Labs’ 1864 Accelera-
tor, a fintech-focused startup accelera-
tor in Egypt, among others.
While this means that the region’s
aspiring entrepreneurs will now have
plenty of options to choose from to
pursue their respective fintech ven-
tures, DIFC believes that FinTech Hive
will be set apart thanks to its emphasis
on “ground-up development.” Accord-
ing to Aich, the DIFC environment,
“founded on the largest representation
of global and local financial service
players,” also works in its favor. “Unlike
most other accelerators globally, where
the financial hub and the fintech hubs
are two separate districts, DIFC intends
to create a hub that serves as a plat-
form for both parties under one roof
to exchange ideas and learn from each
other,” he notes.
Page 74
Entrepreneur february 2017
74
Keeping things local
Jordan-based CashBasha enables MENA shoppers to shop on international
e-commerce portals like Amazon- with cash
By Sindhu Hariharan
ecosystem | who’s got VC | Q&A | STARTUP FINANCE
start it up
“It is surely an interest-
ing time in the region for
e-commerce, as major
business leaders are just
taking notice and there are
talks that billions more
will be poured in regional
funding.”
Fouad Jeryes,
co-founder,
CashBasha
at Startup
Istanbul 2016
H
ere’s a scenario
that should sound
familiar to those of
you in the MENA
region: you’re just
a few clicks away
from completing a
purchase on an international
e-commerce site on which
you’ve found that fashion
accessory or favorite book not
available in the country you
are in, but then, at check-
out, you find that either the
site does not recognize your
credit card, or that the cost of
shipping exceeds the product
price. Jordanian startup Cash-
Basha’s team observed this
emerging market-centric issue
to be ripe for a tech solution,
and thus built a platform that
enables MENA shoppers to
buy from global e-commerce
portals such as Amazon, and
pay for your order with cash.
“We’ve built tools that offer
an automated, transparent
and all-inclusive service right
to your doorstep, as if you’re
being served directly by the
site itself, but with all the
locally preferred emerging
market means of transaction,
delivery and support,” says
Fouad Jeryes, co-founder,
CashBasha.
CashBasha co-founders
Fouad Jeryes and Sinan
Taifour’s entrepreneurial
pursuits started off in early
2013 after stints in various
tech companies, encour-
aged by the fact that their
skills were complementary
in nature. The duo launched
PayHyper- a cash collection
network, which introduced
a creative solution for the
issues surrounding cash on
delivery (COD) by flipping
it as “cash before delivery.”
PayHyper was a combina-
tion of physical locations and
networks of couriers, where
customers can shop online
and pay for them in cash at
trusted locations near them,
or at their doorsteps. The de-
cision to pivot from PayHyper
and start CashBasha was a
result of extensive research by
the team, which showed them
that 80% of e-commerce
retail in the MENA region
was flowing from major global
e-commerce players. “We
believe that one of our success
points is that we’ve been able
to map how emerging market
customers want to be served
onto international shop-
ping sites in [a] manner that
hides all the complexities of
purchasing from the customer
completely,” Jeryes says.
In this endeavor to build
a tech platform that allows
the “unbanked” population
to shop without logistical or
pricing hassles, the CashBa-
sha team ensured that their
solution supported any and all
shopping sites. But currently,
they are partnered with just
one site- but it’s a great first
partner to have, given that it
is global e-commerce major
Amazon. “[We] chose to begin
with Amazon because our re-
search had shown that about
40% of any online purchases
being made in our [MENA]
region all came from that one
site.” Without elaborating on
the terms of the partnership
with the e-commerce giant
(owing to non-disclosure
agreements), Jeryes says that
though “strategically, we’ve
[CashBasha] aligned with
Amazon, we’ve designed our
technology to be agnostic
and work on any e-commerce
website by design.” He adds
that they have received
requests from customers to
integrate more sites, and are
considering it, but are also
“very happy with the tightly
coupled experience we’ve
built” with Amazon.
As entrepreneurs, Jeryes says
that both Taifour and he were
very clear on challenging
themselves at the very begin-
ning when it came to proof of
concept. Launching CashBa-
sha officially in May 2015,
the founders were pleasantly
surprised at the early results.
“So, we decided that we had
to receive 60 orders from cus-
tomers that we had absolutely
no connection to, and without
any marketing in the first
month,” he says. “We were
able to achieve those within
the first two days of opera-
tion. We knew we were solv-
ing a big problem, and growth
has been surprising, to say the
least.” Currently, in Jordan
alone, CashBasha claims to be
shipping nearly “six tons of
goods a month.” The startup
also offers its services in ma-
jor markets like Saudi Arabia,
Page 75
february 2017 Entrepreneur
75
“We do not necessarily
advocate or overly
encourage cash
payments, in fact, we want
customers to transact
in whatever way they are
comfortable with.”
The modus operandi
How does CashBasha work
1. Search for the product
you’d like to buy from Amazon
through CashBasha’s inte-
grated website.
2. Place the item in your
shopping cart as you normally
would, and checkout.
3. At checkout, select pay-
ment method, and other order
details to place the order.
4. In case of cash payment,
the startup’s customer service
team will pick up the cash
amount at your door and
present a confirmation receipt.
Credit card payments can also
be made through the portal.
5. Finally, the goods reach the
customers in a timeline that
depends upon where they are
being shipped.
www.cashbasha.com
Fouad Jeryes,
co-founder,
CashBasha
at Startup
Istanbul 2016
IMAGE CREDITS: CASHBASHA
>>>
and plans to expand its offer-
ings in other regions of the
MENA, with four countries
in the pipeline. However, the
entrepreneur confesses that
the team has been careful to
not “overwhelm themselves”
at any point in time, and is
focused on providing the
best customer experience by
partnering with local teams.
It is this full circle customer
experience and the ease of
shopping from Amazon’s
global catalog that seems
to have contributed to the
startup’s growth. According
to Jeryes, another factor that
drives customers to transact
with them includes a feature
enabling Arabic search. In ad-
dition, he also talks about an
alert system where customers
are informed if a particular
item in their basket is pro-
hibited from being imported
into the destination country,
ahead of order confirmation.
CashBasha also claims to have
engineered proprietary cus-
toms algorithms to keep track
of any changes in packages
as they come through. Citing
these features, Jeryes empha-
sizes that despite the pres-
ence of competition, “none
have produced a seamless and
automated technical solution”
as CashBasha has.
While the business serves a
crucial purpose, I can’t help
but wonder if CashBasha is
limiting itself to customer
groups who still prefer and
use cash for e-commerce
transactions, which, as per
most industry reports on
digital payments, is a reducing
class. I voice this concern,
and also ask Jeryes about
how comfortable he is to be
advocating payments in cash
for e-commerce. He is quick
to respond that CashBasha is
an “e-commerce technology
startup,” and they see cash as
“the preferred means of trans-
action for the next 15 years, at
least according to some cred-
ible studies,” He adds that in
the cash-dominated markets
served by CashBasha, only
20% of the transactions are
digital in nature. Additionally,
he points out that CashBa-
sha’s tools also aid in inter-
national sourcing, shipping,
customs clearance and other
allied needs, and are not just
a means of payment. As for
my query on supporting COD,
Jeryes stresses that their
method is “cash before deliv-
ery,” and not COD. “We do not
necessarily advocate or overly
encourage cash payments, in
fact, we want customers to
transact in whatever way they
are comfortable with.”
With respect to financial
support, the startup has man-
aged to gain trust of inves-
tor groups such as Aramex
Ventures and 500Startups,
raising an undisclosed amount
of seed investment from them.
“[We] will be raising a major
round within the months to
come,” adds Jeryes. While
raising money from such
strategic investors can help
bring attention to a fledgling
venture, it comes with its
share of challenges, and Jeryes
says that “the initial terms
Page 76
Entrepreneur february 2017
76
‘TREP TALK
Fouad Jeryes, co-founder, CashBasha
ecosystem | who’s got VC | Q&A | STARTUP FINANCE
start it up
“[We] chose to begin with
Amazon because our
research had shown that
about 40% of any online
purchases being made in
our [MENA] region all came
from that one site.”
CashBasha
co-founders
Sinan Taifour
and Fouad
Jeryes
that were put on the table
were not the most startup
friendly,” but they had made
the right choice of investors.
“We always wish the process
could have been faster, but
larger companies naturally
work at a slower pace,” he
says. Besides the perpetual
funding woes, CashBasha
also had to face a challenge
that is specific to the Middle
East region- issues related to
citizenship and residency. In
early 2014, co-founder Taifour
(a Syrian national who had
lived in Jordan all his life),
had troubles in renewing his
passport owing to the political
situation. To ensure that this
didn’t affect operations, Tai-
four chose to make use of his
German visa and work from
Germany, which brought with
it management challenges.
“Considering the move, we
had to build the site and all
the operational channels of
the business as a two-person
team sitting a couple of thou-
sand miles apart,” says Jeryes.
After persevering through
such hurdles, the past year
has been kind to CashBasha,
with the startup adding a few
key achievements to its name.
CashBasha emerged as the
winner of Startup Istanbul
2016, an event that brought
together entrepreneurs, busi-
ness leaders and investors
from across Asia and Europe.
Coming in first place out of
2,700 startups that applied,
CashBasha was one of the 15
finalists that pitched onstage
to a jury panel including
investors from 500Startups,
Y Combinator, Abraaj Capital,
and others. Another landmark
moment for CashBasha was
when the co-founders were
chosen to have exclusive time
with Amazon’s Jeff Bezos and
five other senior vice presi-
dents of the company, along
with other Jordanian entre-
preneurs, during Bezos’ visit
to Jordan in November 2016.
Posting on his Instagram page
about the experience, Jeryes
called it “a milestone in our
careers, and we couldn’t be
more thankful.”
Jeryes also carries the same
excitement to the business’s
future. He believes that
CashBasha is poised to pursue
and succeed in a number of
opportunities. “It is surely
an interesting time in the
region for e-commerce, as
major business leaders are
just taking notice and there
are talks that billions more
will be poured in regional
funding,” he says, referencing
recent regional developments.
Noting that the “hunger for
differentiated products, at
competitive prices” among
MENA consumers is not any
different from aspirations of
established markets, Cash-
Basha wants to keep at their
mission of ensuring that no
one is “limited by what you
can, and cannot, buy online.”
What’s your take on the
evolution of the entre-
preneurship ecosystem in
Jordan and MENA?
“Over the past six years, quite
a bit has happened. The build
up of awareness, and attention
towards technology startups
is inspiring, but we aren’t
too far from the starting line.
Although, now perhaps cliché
after seven years, Maktoob’s
acquisition is still the most vis-
ible event that has taken place,
sadly. We remain optimistic
that more success is to follow,
but we would argue that the
type of success entrepreneurs
should be looking for needs to
be in check. Smaller and more
frequent wins, exits or mergers
are more realistic and worthy
of the current market pace.
Amongst these well-positioned
and focused companies, we’ll
surely see more promising
candidates with the ability to
grow into larger entities.”
What’s your advice for
entrepreneurs on fundrais-
ing and maintaining better
relations with investors?
“[Firstly], work, work, work.
Don’t give investors much
attention, as [when] they may
sidetrack you at the begin-
ning. Make sure you’re visible
and constantly on their radar,
but make sure what you’re
working on is doing well and
presents something promising.
They’ll come to you. [Second],
don’t be dragged down by any
formalities when it comes to
your initial investment rounds.
Consider convertible notes and
startup friendly terms that do
not delay your progress or con-
strict your freedom to experi-
ment. Refrain from forming a
board, worrying about interest
rates, and having to report back
on every move you make. Your
investors need to trust you,
and be there for you when you
need them at the early stages,
but not bog you with their pa-
perwork or nosiness. [Finally],
focus on growth and make sure
you find investors that appreci-
ate and understand that.”
What are your top tips for
aspiring entrepreneurs to
start and scale a business in
the region?
1. Prepare for mental and
emotional strife, then learn
to embrace it. “Being an
entrepreneur is an exhilarating
journey, but you’ll soon realize
that although you know it’ll
be a challenging path ahead,
the ‘type’ of difficulties you’ll
encounter will be tough to
anticipate- no matter what you
do. You will question yourself,
your existence, and be surprised
by your vulnerabilities. It will be
awkward and uncomfortable
a lot of times, but learn to
welcome it with open arms
because it is personal and
professional growth and
development disguised as a
short-lived struggle.”
2. Learn from everyone and
follow no one. “No matter
who they are or what they do,
somehow we’ve found that
there are takeaways from any
interaction you could have, and
gain from them. Some of these
might be in the form of ‘what
to do,’ and others are even
more important ‘what not to
do’s.’ There are a lot of jokers
out there.”
3. Throw yourself in the
deep end, but be sure to ride
a wave if you see one. “In
most cases, the market will
tell you what to pursue, and
what seems to be a bit off the
beaten path. There are always
ways to innovate and introduce
something new or in need, but
you need to look for patterns
and work like hell. You need to
commit yourself to your work
and sacrifice a great deal of
time and resources to see it
through.”
Page 77
Page 78
Entrepreneur february 2017
78
Weaving stories
from data
Natural language generation startup Narrativa uses AI
to generate content at scale By Sindhu Hariharan
ecosystem | who’s got VC | Q&A | STARTUP FINANCE
start it up
“Narrativa is helping
journalists to
focus [on] the real
stories, and leave
the repetitive
data-driven stories
to us.”
David Llorente, CEO,
Narrativa at Flat6Labs
Demo Day
S
evilla won with a re-
sounding 2-0 against
Athletic in Nervión,
which sums up eight
straight wins at home.
Gameiro scored the first one
for the locals and closed the
scoreboard by converting a
penalty kick after Kychow-
iak was fouled. Athletic was
unlucky despite controlling
ball possession, and wasn’t
able to finish any of the
numerous chances that they
had.”
At first glance, the above
looks like a snippet from a
typical post-match report,
put together by a sports
journalist who covered the
game, answering the signifi-
cant what, who, where, and
when questions that govern
such pieces. So what makes
this write-up special? Well,
this particular report was
not written by a human be-
ing- it was put together by
an artificial intelligence (AI)
system, and generated using
rows of numerical data in
just a few seconds.
The AI system that wrote the
above is a product of Narra-
tiva, a natural language-gen-
eration startup based right
here in Abu Dhabi. Launched
in the summer of 2015
by David Llorente (CEO),
Eugenio Fernandez (Chief
Scientist), and Antonio
Moratilla (CTO) -research
colleagues from university
days- Narrativa’s technology
takes complex data sets and
transforms them into human
narratives. “Across differ-
ent industries, we identified
a common problem,” says
Llorente. “There is a need to
create content at scale, and
at a very low cost, [but] at
the same time, we discovered
that there is very low levels
of monetization of the data
that companies produce.”
Hence, with a strategy to
“disrupt the digital content
industry,” Narrativa and its
AI product GabrieleAI help
companies generate “mil-
lions of narratives per day”
with a marginal cost of “less
than five cents per narra-
tive.” To understand the
“disruptive” potential of this
claim, consider this claim
against what Llorente calls a
normal scenario, where one
human can effectively gener-
ate only up to four narratives
a day, and the “hundreds
of dollars” involved in such
human-generated content.
Involved primarily in deliv-
ering news reports, earnings
reports, product descrip-
tions, etc. for its customer
groups including news or-
ganizations, content compa-
nies, and e-commerce firms,
Narrativa is keen to sign
up other industry adopters
too. According to Llorente,
GabrieleAI’s ability to gener-
ate content at scale can be of
huge benefits to growing e-
commerce companies. “One
of our e-commerce cus-
tomers has more than 200
people generating product
descriptions for their prod-
ucts, and now using Narra-
tiva they are able to reduce
this number drastically, and
generate much more product
descriptions than before,” he
notes. He adds that custom-
ers are taken aback at the
“quality of narratives” the
technology produces, and
that it’s almost impossible
for anyone to guess that it
was produced by a computer,
and not a human. As of
now, Narrativa serves three
customers, though it says it
has more than 11 customers
in the pipeline.
As a skeptical (and maybe
a bit smug) journalist, I
quiz Llorente about how
GabrieleAI can go beyond
being a solution delivering
volume and speed to answer
the critical “why” needed
in news reports. Llorente is
quick to clarify that while
Narrativa’s tool is no match
to the sophistication and
analysis that a journalist
brings to a story, the startup
is currently working “with
contextual data” to enrich
narratives. “Narrativa is
not trying to take out the
job of journalists,” he says.
“Instead, Narrativa is help-
ing journalists to focus [on]
the real stories, and leave
the repetitive data-driven
stories to us.” It’s quite
evident that currently, the
startup’s USP is the quantity
of content that they can cre-
ate for companies- that said,
Llorente admits that the
tool’s limitation only comes
from the data itself, i.e. the
problem of not having suf-
ficient data.
With large mainstream
news organizations such as
the Associated Press, The
Washington Post, and many
others already using software
to churn out standard news
reports, financial alerts,
Page 79
february 2017 Entrepreneur
79
Why did you decide to start
up in the UAE, and why did
you align with Flat6Labs?
“We analyzed different business
opportunities around the world
and, as explained before, MENA
region is probably the biggest
opportunity worldwide for
automatic content generation.
Flat6Labs is the perfect accel-
erator program to join and enter
the MENA region. Flat6Labs
comes with the support of
twofour54 and has an incredible
network across the region. Also,
[Flat6Labs] comes with top
mentors and incredible facilities
and staff. Flat6Labs gave us ac-
cess to customers and investors
and helped us to understand
the peculiarities of the markets.
The UAE is a very stable and
well-run country with a need
to diversify their economy
and with a great appetite for
innovation and disruption. On
the other hand, the free zones
allow international companies
and startups to operate within
the region with the maximum
guarantees and with almost no
bureaucracy.”
What tips would you offer for
entrepreneurs to start a busi-
ness in the MENA region?
“First, you need to create a net-
work of contacts and it is crucial
to be present in the region.
Trust and reputation are key
factors to succeed, and you will
need to work hard to gain both.
Second, you need a local part-
ner. This is crucial in order to
understand better how things
work plus [it] will help you to
open doors. In our case, the
partner was Flat6Labs; however
it can be a co-founder, investor
or even a customer. Third, it is
crucial to understand that the
MENA market is a winner-take-
all market and has only place
for winners and being second
is not an option. Investors look
for investments with very large
returns and no investor within
the region will trust you if you
are not able to prove that you
can grow fast and take all.”
‘TREP TALK
David Llorente, CEO, Narrativa
“Customers can train
the technology by
adding new example
narratives, so the
technology learns the
writing style of the
customer.”
David Llorente, CEO,
Narrativa at 48 Forward
IMAGE CREDITS: NARRATIVA
sports reports etc., Nar-
rativa is pitted against grow-
ing competition in the field
globally, but that doesn’t
seem to worry Llorente.
“Very few companies are us-
ing AI, and they use a rule-
based approach instead.” He
adds that compared to sys-
tems using rule-based meth-
odologies, those building
natural language-generation
AI (like Narrativa) “have the
advantage of being learning
systems.” This “learning”
feature is perhaps why Nar-
rativa also allows customers
to customize the technology
using a platform they have
developed. “Customers can
train the technology by add-
ing new example narratives,
so the technology learns
the writing style of the
customer,” says Llorente. In
this way, the system enables
users to define the structure
of the narratives.
Interestingly, while you may
think that emerging markets
like the MENA would be
a few years behind in the
adoption of futuristic AI,
Llorente says that Narrativa
sees this region as one with
the “biggest” growth po-
tential. “The MENA region
counts over 350 million
people, and the total online
content in Arabic is less
than 2%,” Llorente notes.
“There is an increasing need
and appetite for content in
Arabic.” He points out that
that the startup is the “only
company in the world” cur-
rently generating narratives
in Arabic, and this gives
them a clear advantage and
differentiation. Narrativa’s
business plans also reflect
this belief. “By Q2-2017
[second quarter of 2017],
we want to sign four more
medium/large customers
in the MENA region, and
another four in Europe and
USA combined… By the end
of 2017, we expect to hit
revenues of over one million
[dollars], and by the end
of 2018, we expect to triple
that amount.”
To help them edge closer to
these milestones, Narra-
tiva has already raised over
US$250,000 in investment
from investors, including
Next Media Accelerator
from Germany and Flat-
6Labs from the UAE, with
Llorente also pooling in his
own money for his enter-
prise. The startup is also
looking to raise $500,000
currently. “We are look-
ing for a decisive and savvy
investor who shares our
vision and who is willing to,
together, disrupt the digital
content industry,” says
Llorente. And how has the
hunt been so far? Llorente
says that as technology
gets “more complicated,”
the process also becomes
harder. Investors insist on
validating the business by
running pilots, which, inevi-
tably, gets costly and slows
things down. However, that
has not deterred the team,
which has been running pi-
lot projects and demonstrat-
ing the capabilities of their
products to MENA’s inves-
tors. As for the emergence
and growth of businesses
based on AI and associated
technologies, Llorente feels
that time is ripe for such
startups to take a shot at
venture capital and insti-
tutional money, and grow
across sectors.
“AI and machine learn-
ing have not really changed
much in the last 40 years;
what has significantly
changed is the amount of
data available to train the
systems and an incredible
computing capacity that
allow us to speed up the
training of AI,” he explains.
The entrepreneur also
believes that AI, along with
big data and the internet
of things, is helping solve
problems that were “pre-
viously irresolvable” and
hence is impacting status
quo across sectors. One
thing, however, appears to
be a recurring theme in any
AI business- job roles being
done away by rise of auto-
mation. Though unnerving,
it is a result of the complex
times we live in, a phase
that the World Economic
Forum calls the “The Fourth
Industrial Revolution,”
which looks like it’s here to
stay, and Narrativa wants
to make sure that it is well
poised to be a leading com-
pany in such a world.
Page 80
Entrepreneur february 2017
80
I
t’s a common thing for
entrepreneurs to start up a
business to solve a prob-
lem that they personally
face, and that seems to
have been exactly the route
Oola Sports co-founder and
CEO Haya Al Ghanim took
when starting up her venture
that offers women “loose-
fitting and not revealing, yet
contemporary and elegant
sportswear.” According to
Al Ghanim, her company’s
activewear line is for women
who are like her- passionate
about staying healthy, but
want to stay true to their
individual values while doing
so. “It all came from my per-
sonal need,” she remembers.
“I had the desire to enjoy the
great outdoors, while stay-
ing in line with my values
and culture. I love outdoors
sports, and I wanted to be
comfortable while exercising.
Plus, I wanted friends to join
me. If they can’t find the right
clothes to exercise with me,
they don’t even make it for an
outdoor run, for example. The
more I looked into ways to
solve this challenge, the more
I realized how big of a market
it is. That led my partners,
Amina [Ahmadi], Lilian [Bar-
bosa], and I to work together
on finding a solution, and
we decided to launch Oola
to provide more women with
access to outdoor sports by
providing modesty-inspired,
loose-fitting activewear.”
Explaining the name of her
company, Al Ghanim says,
“In Arabic, oola means the
first, the pioneer. We believe
every woman is a pioneer in
her own life, and our brand
reflects this belief. Oola is a
revolutionary brand that ca-
ters to the active woman who
chooses to maintain an active,
healthy lifestyle, while choos-
ing to maintain her individual
values. Our garments are
made for the pioneer in you.”
And for what it’s worth, it
certainly does seem like Oola
Sports has been a pioneer
in whatever it has set out to
do so far. In less than a year,
Oola has grown to be a brand
that has achieved recogni-
tion in Qatar and the region,
with the first batch of its
activewear collection having
hit the market in the last
quarter of 2016. “We came
together for a common goal–
gearing up for the launch,
accepting the challenge to be
agile, and quick to act on a
crowdfunding campaign on
Indiegogo with the teaser,
‘Oola Sportswear: Activewear
That’s Got You Covered’ that
was started in the beginning
of October 2016. This experi-
ence reshaped my expecta-
tions of the new hires on the
Oola team, and in the end,
after 30 days on Indiegogo, we
raised a total of US$33,790
from 115 backers. This was
over and much beyond our
expectation of $25,000.” At
the same time, Oola decided
to make it a priority to cater
to the perspectives of a wide
spectrum of customers.
Detailing her team’s journey
with the feedback process,
Al Ghanim says, “Entrepre-
neurs are often encouraged
and constantly reminded,
borderline nagged, to seek
customers’ feedback. 2016
taught me that despite the
constant reminder, when it’s
time to make decisions, our
default judgment is to go with
our own preference.” In 2016,
Oola developed a customer-
centric product-development
cycle by creating customer
feedback groups for spe-
cific product lines, including
swimwear and the abaya. This
intentional focus on customer
feedback has propelled the
team full-speed ahead with
designing some of their most
innovative pieces. In terms
of manufacturing Oola’s
various products, Al Ghanim
says that when the company
was exploring options in this
space, they went to a trade
fair in Germany that had
suppliers and manufacturers
from all over the world. After
testing product development
with various developers, the
team decided to proceed with
making its first collection in
Taiwan, given the quality of
production and the ethical
standards of the factory. “We
are now in the process of de-
veloping the second collection
in Qatar,” Al Ghanim says.
Coincidentally, when Oola
was being launched, that
was when the burkini (the
full-body swimwear worn by
some Muslim women) ban
was being implemented in
France and other countries
in Europe. When asked about
it, Al Ghanim wasn’t approv-
ing of it, saying, “It’s a matter
of personal preference, since
covering up is not a symbol of
one religion.” She adds that
being modest is something
that is commonly practiced
among those of Islamic, Or-
thodox Judaic, Coptic Chris-
tian, or other religious faiths.
In addition to being modest
or abiding by norms, regard-
less of religious prescriptions,
Driven by purpose
Oola Sports co-founder and CEO Haya Al Ghanim wants to help women
enjoy the great outdoors- while staying true to their personal values
By Aparajita Mukherjee
ecosystem | who’s got VC | Q&A | STARTUP FINANCE
start it up
Products by
Oola Sports
Page 81
february 2017 Entrepreneur
81
Al Ghanim, while speaking to
women during the fine-tun-
ing process of her business
model, says that she “heard
from women who had just
given birth and they are not
comfortable with wearing
fitted sportswear, until they
lose the pregnancy weight.
They were also looking for
loose-fitting activewear, and
it would be a shame to let
clothes prevent them from
enjoying an outdoor workout
or a swim.” From Oola’s per-
spective though, Al Ghanim
reveals that the company is
indeed working on a swim-
wear line for its customers.
“For swimwear, we’re in the
very early phases of gather-
ing consumer feedback, and
we’ve created a WhatsApp
group chat, so that these
women can share their key
needs and insights about
what they’re looking for in
modest swimwear apparel,”
she explains. “We’re excited
that our group includes a
businesswoman (who is very
passionate about a specific
fabric she’d like to see swim-
wear made with), a college
student (who prefers modest
swimwear, but is disheart-
ened by the way current
options drag in the water
and pull her down), and an
aspiring Olympic swimmer
(who is training for a career
in swimming, but who does
not want to take off her head
scarf to participate).”
Al Ghanim’s strategy for
building up Oola’s swim-
wear line is characteristic
of the company’s product
development methodology.
“It always begins with the
customer,” she says. “And it
includes the following steps:
gather consumer feedback
on key needs; sketch various
ideas and ask for feedback on
the ideas; build a proto-
type, based on key sketch
feedback; have users test
prototype and describe ex-
perience; integrate customer
experience notes for final
product design; and test pro-
duction samples with larger
customer base.” Given that
she has such a clear-cut plan
for how to go about building
products for her enterprise,
it seems pretty evident that
Al Ghanim has a lot up her
sleeve for Oola in 2017. “The
year 2016 was all about set-
ting up. Between establishing
our brand awareness, build-
ing the community, growing
the core team, kicking off
sales, fulfilling orders and
developing new products, the
ultimate focus of 2016 was to
get things done. We often did
this apart from one another
with lots of work-from-home
time and on-the-go mad-
ness. I envision more team
time under one roof in 2017.
Though remote work can be
an effective way to give team-
mates more space to focus
and deliver, nothing replaces
the feeling of togetherness
like working side by side
with teammates.” Speaking
of additional products from
the Oola stable, Al Ghanim
mentions: swimwear, triath-
lon suits, horse riding out-
fits. But the overriding phi-
losophy is to keep the door
open for customers to tell
Oola what they want to see
next. “We will also continue
to be involved in community
building efforts to encourage
more women to explore the
beauty of outdoor activities,”
she says. “We’re also on
track for releasing collection
2 in the spring of 2017, with
your favorite colors and most
desired sizes!”
Operating out of the Qatar
Business Incubation Center’s
(QBIC) premises since
October 2016, Al Ghanim
says that she is grateful for
the added support she has
for her enterprise today.
“We feel like our Oola fam-
ily grew and extended to
include many more sup-
portive QBIC staff looking
after our success, and fellow
entrepreneurs sharing their
experience with us and even
exploring partnership op-
portunities.” She adds that
Qatar Foundation has also
taken part in equipping the
Oola team with the educa-
tional tools and encourage-
ment that they needed to
pursue their dreams. When
asked about her wish list in
terms of requests to the Gov-
ernment of Qatar, Al Ghanim
says, “What I believe would
add value to government and
businesses is to bridge the
gap between businesses and
innovative solutions being
built in the labs. This type of
public-private partnerships,
if supported by the right
policies, can result in even
more competitive businesses
and better reach of research
outcomes in the market.” We
agree with Al Ghanim on that
front- and we certainly hope
the changes she wants helps
out Oola in the long run.
Onward and upward!
How important do you think is
it for entrepreneurs to find the
right professional partner in
carving out success?
“Finding the right partner is as
important as finding the right
spouse. For an early-stage
company, it’s critical to build it
on the right foundation of values,
common understanding, similar
work ethics and equal passion.
Having the right partner not
only helps in building the strong
foundation a company needs,
it also makes it much more
enjoyable. That also applies to the
early hires, not just the founders.
I’m grateful for the wonderful co-
founders and core team we work
with for making the Oola journey
enjoyable.”
What would you tell an
aspiring businesswoman in
the region to be prepared for
before she ventures on her
own?
“Businessmen and
businesswomen alike need to be
prepared for the ups and downs
of an early-stage business. I
make sure we celebrate Oola’s
achievements as a team to remind
ourselves of how lucky we are to
have each other and accomplish so
much. This makes it easier to get
through difficult days for sure.”
What have been your biggest
lessons from your journey with
Oola so far?
“The crowdfunding campaign has
raised my bar for new hires. Going
forward, for 2017 onwards, we will
be looking for new team members
to join us, only if they can have the
same agility, responsiveness and
selfless giving of quality work for
the overall betterment of the team
and Oola. Secondly, our goal for
2017 and onwards is to not only
continue to be good listeners to
our customers’ needs, but also
when it’s time to make decisions,
we would refer to their valuable
insights. That’s our priority, and
a determining factor in making
decisions.”
‘TREP TALK
Haya Al Ghanim,
co-founder and CEO,
Oola Sports
IMAGE CREDITS: oola sports
Lilian Barbosa, Haya Al Ghanim and Amina Ahmadi, co-founders, Oola Sports
Page 82
Entrepreneur february 2017
82
How to ensure your business enjoys long-lasting success
By Suzi Croft and Manar Al-Jayouchi
For the long haul
Suzi Croft and Manar Al Jayouchi are the co-founders of the Appetite Group.
Appetite - The Shop at
Index Tower, Dubai
Appetite -
The Shop
at Business
Bay, Dubai
ETHICS | ESQUIRE GUY | SKILLSET | MARKETING | PRO
TREPONOMICS
It’s one thing to start a business-
it’s another thing altogether to keep it
running sustainably and successfully
over a number of years. We started Ap-
petite over 11 years ago, when we saw a
gap in the market for wholesome, grab-
n-go food. As a small enterprise that
started in Dubai with just two employ-
ees, we have since managed to achieve
great success over the years, and now,
more than a decade later, the Appetite
Group umbrella includes homegrown
concepts like 1762 Deli, 1762 Stripped,
and more. It’s been a long journey get-
ting here, and for those of you entrepre-
neurs just starting out on this ride, here
are a few tips that we think can help you
along with this trip:
1. Build a good team spirit Creating
the right company culture is always a
challenge. Over the years, we have been
very lucky to have some of the best and
brightest join us on our journey. At the
end of the day, every aspect of our com-
pany is made up of people, and happy
people perform, not only at their jobs,
but also in their personal friendships,
and work relationships.
2. Creativity is key Creativity plays
a pivotal role in our company, maybe
more so then others. We’re hitting this
in every department, from our interiors,
product development, marketing, and all
the way up to staff uniforms. We strive
to bring in creative minds into the mix
at any opportunity as it plays a central
position in our daily discussions.
3. Keep up with technology 2017 is
the year of digital for us. An important
factor in any industry now is to stay
loose and nimble. Technology is chang-
ing daily (though we still can’t see the
day of eating a digital sandwich!), and
it touches heavily in our operational ef-
fectiveness and marketing department.
As in all things with our business, we
try to stay one step ahead of the game,
whether that’s bringing new foods in
to the mix, or ensuring we’re connect-
ing with people on the right platform.
As much as this comes in to play, we
will always place value, and endeavor
to have that human touch behind the
scenes, to bring warmth and openness
in to our brands.
4. Stay true to your values Product
consistency has always been a challenge.
Weather patterns change, ingredients
shift, trends differ. Making sure we put
out to market a consistent offering that
ticks all the boxes, whilst staying on
point to our company values is the chal-
lenge. That’s why we sample, taste, and
push for feedback every day, whilst still
keeping one eye on the future.
5. Think global We have a fantastic
consumer base in the UAE; it’s one of
the most diverse in the region, full of
brilliant minds and forward thinking
people. The downside of this is that
people aren’t always here for the long
haul. The world is a much smaller place
now and people move around constant-
ly, this means our connectivity becomes
dated very quickly. Tackling this is a
self-discipline to constantly shout and
be out in the limelight. We bring in
new friends and customers, and slowly
but surely build a strong global brand
reputation.
6. Customers need to come first
(always) Product, service, and strategy:
these are the three supporting points of
any hospitality business. Food tasting
has become a daily ritual for us. We
draw inspiration from around the globe,
and always push to innovate ahead of
the competition in every aspect of our
business. Service aspects, we cover with
very thorough hiring policies to ensure
an amazing management team, and the
strategy side is tackled on our aspira-
tions to lead the food and beverage
industry in the Middle East.
Finally, our advice for entrepreneurs
setting out on building their enter-
prises: it’s a lot of hard work. Nothing
will prepare you for that, but on the flip
side, you’ll never feel happier having
produced something so beautiful for
yourself. Focus on location, product
and service- if you hit the big three, you
certainly won’t be too far off the mark.
Page 83
Page 84